A Gym With a Cinema. Nobody Here Really Cares About Working Out. SeaPRwire

A Gym With a Cinema. Nobody Here Really Cares About Working Out.

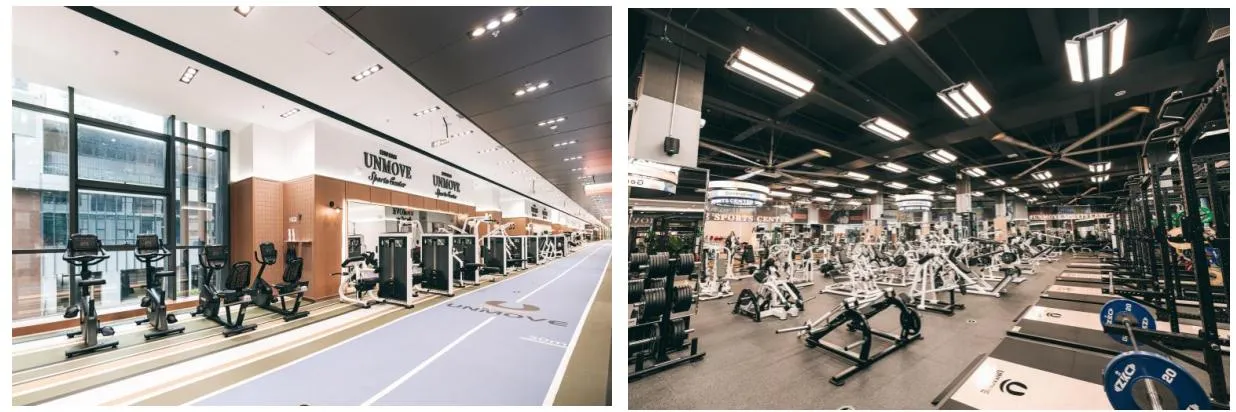
“Ten days in Shenzhen, and UNMOVE is the only place that didn’t rush me.” — an APEC visitor who came to the city early At seven on a Tuesday, the cinema inside UNMOVE is quiet. In a building of 10,000 square metres, UNMOVE gave its quietest corner to a screen and two rows of treadmills. Ten or so people are walking, not fast, incline set somewhere between flat and steep, eyes on the screen. Most of them came for the film. The film is a licensed action release, and the volume sits in a narrow band: loud enough to cover the hum of the treadmills, quiet enough that two people could talk without raising their voices. Daniel Ho stood in the doorway for a while before going in. He flew in from Singapore ten days early for APEC, with three meetings booked with industrial robotics suppliers and a fourth that fell through that afternoon. “I only came here to take a shower,” he said later. He stayed an hour and a half. The room doesn’t behave like a gym. Nobody shouts. Nobody drops a barbell. Nobody photographs himself in the mirror. The light comes off the floor in a soft ring, the walls are black, and the only thing moving is the film and the slow rise and fall of people walking. “In Singapore I run facing a wall,” he said. “Here I run facing a movie. You walk, and forty minutes are gone.” That is the whole trick, and it is not really about the movie. The room is comfortable enough that training stops being the main event. It becomes the thing you do while you are in there. The workout is a by-product. Why a fund manager from Singapore is in Xili on a Tuesday Ho is 38, a partner at a Singapore fund that backs factory-automation companies, and the kind of traveller who books a gym before he books a hotel. Shenzhen this month is full of people like him. APEC is the city’s biggest week of the year, and it has brought a few thousand executives, delegations and advisors to town; a good number of them arrived early to see things beyond the summit itself. His hotel has a gym in the basement. Three treadmills, one broken screen, no windows, and a sign asking guests to limit sessions to thirty minutes. He lasted two days. He has a routine for this. Find one place with decent free weights within twenty minutes of the hotel, pay for a week, accept that it will be either too cold or too hot, and stop thinking about it. In nine years of work travel he has done it in eleven cities and can list them in order. A colleague from a portfolio company sent him a message with an address in Xili. “He said: try this one, it’s not like the others.” So on his third night, after a factory tour in Bao’an that ran long, he took a car across the city to a 10,000-square-metre building he had never heard of. The room took a film contractor to build Most gyms with a screen buy a projector, hang it on the wall, and leave a nature loop running. UNMOVE hired a cinema engineering team. Treated acoustics, sealed walls with a separate ventilation balance, cinema-grade projection and surround sound. Sealed but ventilated is the difficult part. Get it wrong and the room is either airless after ten minutes or loud enough to give you a headache. Two hundred square metres, two long rows of treadmills and ellipticals, and light that comes from the floor. There are no downlights over the machines. A ring of diffuse lamps traces the edge of the walkway, which is why you can run in near-darkness without worrying about stepping off something. The films are licensed and current, chosen for pace rather than plot. A nature documentary will not hold anyone through twenty-five minutes of incline walking. A car chase will. “The first thing I noticed was that nobody was watching the film properly,” Ho said. “Then I realised that was the design. You’re not supposed to sit and watch. You’re supposed to walk, and let it pull you along.” Twenty metres inside the door The first thing is the smell. Something citrus and wood, constant, too faint to name. Then the air, which does not have the gym smell: the warm, close, slightly sour air of two hundred people breathing in a sealed box. The fresh-air system runs in zones, so the room held at 40 degrees does not share air with the weight floor. Then the sound. There isn’t any, or not much. No playlist competing with the machines, no coach with a speaker at the front desk. The flooring takes the footfall. “For the first minute I thought the place was closed,” Ho said. “It’s that quiet. In most gyms the noise is the first thing that hits you, and you brace for it.” Why the machines are the expensive, forgiving kind The machine floor at UNMOVE holds more than three hundred pieces, from Panatta, Life Fitness, Precor, Nautilus, Freemotion and NordicTrack. Almost all of them are pin-loaded, the type where you push a pin into a stack, rather than plate-loaded, where you hang steel plates on the ends of a frame. That is the reverse of what most large Chinese gyms do. Plate-loaded equipment is cheaper, takes more abuse, and is what serious lifters ask for. It is also less forgiving: the resistance is whatever the plates say, the path is fixed by the frame, and a beginner with bad shoulder mechanics will load it wrong and get hurt. Ho noticed within about ninety seconds. “You can tell from the first rack. This is a gym for people who have jobs.” He trains four times a week at home and counts himself somewhere between committed and obsessive. “At my club, half the floor is plate-loaded, because the members want to feel the weight. Here the weight is the same, it just doesn’t punish you for being tired.” None of which makes the equipment soft. The stacks go heavy, the paths are standard, and a serious lifter will still fail on the last rep. The difference is that the machine doesn’t punish a bad rep. The barrier is whether you’ll train, not whether you dare. Where ten thousand square metres goes A building this size can hold things a 1,500-square-metre gym cannot. Some of it is expected: a Les Mills studio running the full programme, a hot yoga room held at 40 degrees with an imported programme rather than a space heater and good intentions, a boxing ring built to competition spec. Some of it is not. There is a 500-square-metre HYROX-certified training area laid out like the race itself, sleds and sandbags and all, which means somebody here can prepare for an international fitness race on the same floor plan they will compete on. There is an indoor pickleball court. Ho found that one on his second visit, and by Thursday he had a game booked with two Germans he met at the net. “The pickleball court is the thing that convinced me this place understands who lives here,” he said. “Nobody builds a court for a sport nobody plays unless they’ve watched people try to find one.” The cold room, and what happens after you train The recovery wing at UNMOVE sits behind the cinema, in the same corridor as the stretch boards: a liquid nitrogen cryotherapy chamber, a medical-grade hyperbaric oxygen chamber, an infrared sauna, a steam sauna, compression boots. Ho went into the cryo chamber on his first visit, on the theory that fourteen hours in a seat followed by two factory tours is a good reason to be frozen for three minutes. Socks, gloves, vapour, an attendant with a timer telling you when to turn. Not pleasant. Over quickly. “Afterwards I could walk down stairs like a person,” he said. Whether that is physiology or a placebo, neither of us can say. What is true is that everybody who came out had the same look on their face, the look of someone who has just got out of a meeting. The room was busy at seven on a Tuesday, mostly with people in their forties who had come off the weight floor. The assessment that isn’t a sales pitch Most gyms in China offer a body composition test. You stand on a machine, it prints a number, and the number is used to explain why you need twelve sessions. UNMOVE runs it in three layers, which takes longer and is harder to turn into a script. Three layers: baseline physical data, then a conversation about how you actually live (sleep, sitting, travel, when your back hurts), then a functional screen for movement and pain. It repeats monthly. “In Singapore the free body scan always ends with a package,” Ho said. “Here they told me what was wrong with my hip and then let me go and use the gym. I kept waiting for the sales part. It didn’t come.” The monthly part is the interesting one. A single assessment is a sales tool. A monthly one is a record, and a record will eventually show that a plan isn’t working, which is not what a commission-driven floor wants a member to own. The price board That is how UNMOVE prices things: on a board by the door. Not in a folder that a consultant opens after you have been walked around for forty minutes: printed, in the open, for every class and service they sell. Membership is monthly. No annual card to be upsold into, no hidden extras folded into the sign-up. If you want to leave, you leave, the refund is unconditional, and nobody asks you to come and discuss it with a manager. Nobody at the front desk earns commission on what you sign, which is the rule that changes all the others. A floor without commission has no reason to walk up to you mid-set. For Ho, this was the practical question. He is in Shenzhen for three weeks and then goes home. “I’ve joined gyms in six cities for a month at a time. It’s always the same conversation: sign for a year, we’ll freeze it, don’t worry. I don’t want to sign for a year. I want to pay for three weeks.” He signed up on his second visit. One month, refundable, cancellable when he gets on the plane. Choc Choc looks like he is in his late twenties. Years of training will do that, and he is happy to let people assume it until he finishes a sentence. He spent nearly a decade running gyms outside China, from coaching to regional operations, and has executed most of the industry’s playbook himself. He was in his mid-thirties when he came back to Shenzhen to open UNMOVE. “It wasn’t that I couldn’t do the maths,” he said, laughing. “It was that once I had, I didn’t want to train in the place the maths produced.” He talks slowly, uses examples from ordinary life, and stops mid-conversation to ask whether you want water. Halfway through our talk he got up to greet a member who had just finished working out: first name, two questions about her kid’s school, then back to the sofa. “We’re not in the equipment business,” he said. “Anyone can buy a Panatta machine. The hard part is the room it sits in, and the rules around it.” The company’s stated order of values is joy, then freedom, then expertise. It sounds like marketing until he explains it the way you would explain it to a friend. Joy first, because nobody keeps doing something that isn’t fun. Freedom second, because “you have to let people leave before they’ll stay”. Expertise third, because once the first two are true, that is what people are staying for. He is in the building six or seven hours a day: one hour of training, the rest spent in the lounge, talking to members, drinking coffee, noticing what is not working. “Most of my job is sitting here,” he said. “Watching who comes in tense and whether they leave looser.” On the industry, Choc is brief. “Everyone in this city is trying to get people through the door. What happens to them after the door, nobody seems to think about.” Eight o’clock Ho left at eight, past the man asleep with a book on his chest, past the stretch board where somebody stood on one leg, scrolling. Outside, Shenzhen was doing what it does at eight on a Tuesday: three lanes of traffic, delivery scooters, a man selling roasted chestnuts out of a drum. He has two more supplier meetings before the summit, then four days of APEC sessions on a schedule he calls worth the trip, then a flight home. He will come back to UNMOVE three or four times, use the cryo chamber after the long days, and cancel the membership from the airport. That is the entire transaction, and it is the point. A gym that lets a man pay for three weeks and leave without a fight has nothing to lose from him, and everything to gain from the fact that, next year, he will tell a colleague to go. “Ten days in this city,” he said, at the door. “UNMOVE is the only place that didn’t rush me.” Reporting note: facility details — floor area, equipment brands, zones, recovery equipment, pricing rules and assessment structure — were supplied by UNMOVE and have not been independently audited. The visiting executive is a composite drawn from interviews with foreign members during APEC week; his name and employer have been changed. Choc’s remarks are drawn from an interview and should be confirmed with him before publication. For inquiry related to UNMOVE, please connect zhaochuang@unmove.cn
More
UNMOVE Launches Seven-Day Pass and Short-Cycle Personal Training for APEC Visitors in Shenzhen SeaPRwire

UNMOVE Launches Seven-Day Pass and Short-Cycle Personal Training for APEC Visitors in Shenzhen

The Xili sports and recovery centre adds flexible passes and 10- and 12-session coaching packages for international guests on tight schedules, open to all members at home and abroad SHENZHEN, CHINA — UNMOVE, the 10,000-square-metre sports and recovery centre in Shenzhen’s Xili district, today announced a seven-day pass and two short-cycle personal training packages, developed for the international professionals in the city for APEC 2026. The seven-day pass gives full access to the facility. The training packages run 3 sessions over 7 days, or 9 sessions over 21 days. All three are offered at introductory rates through the APEC period and are available to every member, Chinese or international. APEC 2026 has brought several thousand delegates, executives and advisers to Shenzhen, most of them for one to two weeks. Their days are scheduled from morning to evening, and the hour they would normally spend training is usually the first thing to be cut. Many of them train daily at home and intend to keep doing so here. “People who train every day don’t stop when they travel,” said Choc, chief executive officer of UNMOVE. “What stops is their access. They land in a new city, the hotel gym has three machines and a thirty-minute limit, and by the seven day the habit is gone. A monthly membership doesn’t solve that for someone who is here for nine days.” The shorter cycle is also a response to how visitors use coaching. A standard personal training block of 20 or 30 sessions assumes a member who will still be in the same city in three months. For a guest on a two-week stay, most of that block goes unused, and the sessions that do happen are compressed into the last few days. “9 sessions in 21days is not a smaller version of a normal package,” Choc said. “It’s the right size for someone with a deadline. They can train every other day, and the last session still means something.” The seven-day pass covers the whole building rather than a single zone: more than 300 pin-loaded machines from Panatta, Life Fitness, Precor, Nautilus, Freemotion and Newtech; a 200-square-metre cinema cardio room; a Les Mills studio; a 40-degree hot yoga room; a 500-square-metre HYROX-certified training area; a competition-spec boxing ring and a pickleball court; and a recovery wing with liquid nitrogen cryotherapy, medical-grade hyperbaric oxygen and an infrared sauna. On pricing, Choc was direct. “We set one price list and applied it to everyone,” he said. “Visitors shouldn’t pay more than the people who live here, and the people who live here shouldn’t find out that a guest from out of town got a better deal. It’s the same card, the same rate, the same terms.” UNMOVE opened in Xili with a membership model built on monthly billing, published pricing and no commission at the front desk. The centre says the short-cycle products follow the same principle: a member who wants to leave can leave, and a visitor who wants three days should not have to buy a year. The seven-day pass and both training packages are available at the UNMOVE front desk in Xili and through the centre’s official booking channels from today. Pricing details and terms are available on request. About UNMOVE UNMOVE is a 10,000-square-metre sports and recovery centre in Shenzhen’s Xili district. Its facilities include a 300-machine training floor, a cinema cardio room, a Les Mills studio, a hot yoga room, a HYROX-certified training area, a boxing ring, a pickleball court and a recovery wing offering cryotherapy, hyperbaric oxygen and infrared sauna. The centre operates on monthly membership, published pricing and a three-layer physical assessment renewed each month. Media contact Brand: UNMOVE Contact: Media team Email: zhaochuang@unmove.cn
More
Soo & Carrots Announces Soo House Platform Connecting More Than 70,000 Foreign Residents in Korea With Paid Brand Campaigns, Surveys and Gigs SeaPRwire

Soo & Carrots Announces Soo House Platform Connecting More Than 70,000 Foreign Residents in Korea With Paid Brand Campaigns, Surveys and Gigs

The Seoul-based company’s app matches foreign residents with brand and public-sector projects that call for a specific language, nationality or cultural perspective, with no minimum follower count SEOUL, South Korea – November 03, 2026 – (SeaPRwire) – Soo and Carrots, a Seoul-based company that connects Korean brands and public institutions with foreign residents, announced that its Soo House app now brings together paid brand campaigns, consumer surveys, short gigs, job listings, auditions and an expat community for more than 70,000 foreign residents in Korea. Soo House users at a community meetup and brand campaigns (left), and the app flow from finding an opportunity to receiving redeemable points (right). Brands and public institutions use Soo House to reach foreign residents for projects that require a specific language, nationality or cultural background. A skincare brand preparing to enter Southeast Asia, for example, may ask Vietnamese or Thai consumers how they read its ingredient labels. A regional tourism office may commission Japanese-language content from visitors who have been to the destination. Each brief treats the participant’s background as the qualification for the task. “Running programs for foreigners is not the hard part. Reaching the people who need them, and keeping them engaged until the end, is,” said Soo Kim, chief executive of Soo and Carrots. “We have tried to connect foreign residents with Korean society and businesses not as people who receive help, but as participants who learn, work and create value.” Participation without a large following / requirement According to the company, most Soo House users are not professional creators. Alongside creator campaigns, the app lists consumer surveys, service feedback tasks and event reviews that do not require a social media account. A feedback task may involve testing a delivery app, a banking service or a tourist pass and reporting where it becomes difficult for a non-Korean speaker. For creators, campaigns cover product seeding, venue visits and nationality-specific casting across beauty, food, lifestyle and travel. Soo House sets no minimum follower count. Individual campaigns screen for language, nationality and lifestyle fit instead. The company said a creator with 3,000 closely connected followers in a target market can be more relevant to a brand entering that market than a larger account in a different language. Each listing states its task, deliverables and reward before users apply. Once a submission is approved, participants receive Soo House Points, which can be redeemed for mobile vouchers, withdrawn to a Korean bank account or loaded onto a prepaid card. Minimum amounts, fees and processing times are shown in the app. Registration is free for foreign residents in Korea aged 18 or older. Most listings do not require Korean language skills, although some in-person events ask for basic Korean. The company notes that eligibility for cash rewards may depend on a user’s visa status, as some activities can count as income. Programs with public institutions and enterprises Behind the app, Soo and Carrots Inc. operates the campaigns and programs that clients run on Soo House, handling participant recruitment, multilingual on-site operations and post-event reporting. In August 2026, the company ran lots of career programs for foreign residents with the Seoul Global Center, such as auditions for foreign jobseekers and cultural festivals. The company has also organized global festivals with Hyundai Department Store Group, including events at Hyundai Outlet Dongdaemun where foreign residents and creators recruited through Soo House sold, sampled and introduced products. For COMEUP, the startup festival hosted by the Ministry of SMEs and Startups, Soo & Carrots ran the foreign pre-registration campaign, work that earned the company a Minister’s Award in 2025. Availability Soo House is available on the App Store and Google Play. More information is available at https://landing.soohouse.app/. Brands and institutions seeking to work with foreign residents in Korea can contact Soo & Carrots at https://www.sooandcarrots.com/. About Soo & Carrots Soo & Carrots is a Seoul-based company that operates Soo House, an opportunity platform for foreign residents in Korea. The company connects Korean brands and public institutions with foreign residents through creator campaigns, participant recruitment, career and education programs, global events and consumer research. Soo & Carrots received the Minister’s Award from the Ministry of SMEs and Startups in 2025 and the KOSME Chairman’s Award in 2024. It is a certified venture company and social venture founded under the mission “Opportunities For Foreigners.“ Media Contact Company: Soo and Carrots Inc. Contact: Soo House CS Email: help@sooandcarrots.com Website: https://landing.soohouse.app
More
The 7.7-Million-Job Industry That Still Runs on Phone Calls SeaPRwire

The 7.7-Million-Job Industry That Still Runs on Phone Calls

CieloAmor Travel & Tours and the fight to build a trusted booking layer for Philippine travel The call comes in around mid-morning at a walk-in office on Diversion Road Boulevard in Teresa, a municipality in Rizal province, east of Manila. A family wants a van to the airport, a resort in Palawan and a day of island hopping in Bohol — three suppliers, three deposits, three sets of cancellation rules, none of them written down anywhere the family can read them. CieloAmor Travel & Tours, the agency that runs the office, spent most of its working life answering exactly this kind of call. In January 2027 it opened a website, cieloamor.com, that tries to put the same trip into one booking flow. The timing is not accidental. Tourism is one of the largest industries in the Philippines by almost any measure. The Department of Tourism’s figures put international arrivals at 6.44 million for 2025 including balikbayan residents, tourism receipts at PHP 694 billion, the sector’s direct contribution to GDP at 8.1% and tourism employment at 7.7 million jobs. For an economy of roughly 110 million people, one in fourteen workers depending on travel is not a niche. It is a pillar, and it is the pillar CieloAmor was built to serve. And yet the layer that connects all those workers to their customers — the booking layer — runs largely on phone calls, Facebook messages and cash deposits. CieloAmor’s founder, Julieann Rebanal, put it in the company’s launch statement: booking apps have shown Filipinos how easy booking online can be, but many local hotels and operators are still not online, and travelers still want someone they can call. This article looks at what stands between those two sentences, because the space between them is where a large part of Philippine tourism policy, payments and small business will be decided over the next five years. A market that counts itself three ways The first thing anyone studying Philippine tourism learns is that the country’s headline numbers depend on who is doing the counting. In the first eight months of 2026, the Department of Tourism’s eTravel system recorded 4,115,860 foreign visitors. The same period, counted on the merged caliber that includes returning Filipinos, comes to 4,415,860. A third figure circulating through Chinese-language community press put it at 4.4 million flat. The gap between the two main calibers is almost exactly 300,000 people — about 7.4% — and the difference is a single question: whether balikbayan, Filipinos residing abroad who return home, are counted as visitors. Neither number is wrong. But the practice of publishing both, without one authoritative series, tells you something about the administrative maturity of the sector’s data layer. An industry that cannot settle on how to count its own arrivals will struggle even more to measure something harder, like what share of its transactions happen online, or how many of the country’s small hotels and tour operators are bookable through any digital channel at all. The rest of the statistical picture is more solid. The table below assembles the main published figures. IndicatorValuePeriodSourceInternational visitors, incl. balikbayan6.44 million2025DOT, via Central News AgencyTourism receiptsPHP 694 billion2025DOT, via Central News AgencyDirect contribution to GDP8.1%2025DOT, via World NewsTourism employment7.7 million jobs2025DOT, via World NewsVisitor target6.6 million2026DOTCumulative visitor growth3.46% YoY2026 to datePhilippine Business News Growth is real but unspectacular. The 3.46% year-on-year increase recorded so far in 2026 trails what the government needs to hit its 6.6 million target for the year, and it is far below what the region has set for itself. At the 29th ASEAN Tourism Ministers’ Meeting, held in January 2026 in Cebu — the first time the Philippines has chaired the meeting in years — ASEAN reported roughly 144 million international visitor arrivals for 2025 and endorsed a 2026–2030 strategic plan targeting cumulative growth of 51%, an annual average of 8.7%. A separate regional business bulletin projects arrivals reaching 201 million by 2030. The Philippines, in other words, is being asked to grow at nearly three times its current pace by a regional framework it helped write. That arithmetic is the quiet pressure behind everything in this article. Growth of 8.7% a year does not come from adding more international flights alone. In every Southeast Asian economy that has sustained growth at that rate, a large part of the gain came from the domestic and long-tail market — the weekend trips, the provincial resorts, the family reunions in the next region — and that market books differently from the international one. The habits travelers bring with them Filipino travelers do not lack digital experience. What they lack is a digital layer built for them. The booking habits that the region’s biggest travel economies have normalized give a rough picture of what Philippine travelers will eventually expect. MarketScale markerBooking-layer implicationChina6.52 billion domestic trips, CNY 6.3 trillion spending (2025)Super-app booking is the default; installments are a mature consumer-credit productThailand205 million domestic trips targeted for 2026; THB 1.53 trillion foreign revenue in 2025Domestic volume dwarfs international; platforms compete on local-language supplySingapore16.9 million arrivals, SGD 32.8 billion receipts in 2025; SGD 1,941 per visitorHighest per-visitor spend in the region; every transaction is digital-firstIndonesia1.25 billion domestic trips targetedArchipelago geography forces multi-leg booking — flights, ferries, vans in one flow Three of these four markets are neighbors of the Philippines, and the fourth is its most important future source market. China’s domestic tourism engine — 6.52 billion trips in a single year — was built on platforms that let travelers book a hotel, a train and a theme-park ticket in one app, pay in installments, and get a human on the phone when something breaks. Thailand’s target of 205 million domestic trips in 2026 implies that the average Thai household travels domestically several times a year, on bookings that are overwhelmingly made through digital channels with local-language support. The Philippines sits between these models. Its own domestic travel volume is not published in comparable series — a telling absence in itself. What is visible is the friction that travelers describe: paying in full upfront for a package, sending deposits to unaccredited sellers found on social media, and coordinating a single trip across a hotel, a van rental and a tour operator who have never spoken to each other. The ASEAN comparison suggests the demand exists. The missing piece is the intermediary layer. Four ways a Philippine trip gets sold The supply side of Philippine travel booking is not one market. It is at least four, with different economics and different failure modes. The first is the global OTA layer. International platforms book the country’s international arrivals efficiently — the 818,318 American visitors recorded on the eTravel caliber in the first eight months of 2026, or the 727,379 South Koreans on the same caliber, largely book flights and chain hotels through platforms designed for them. But that same layer performs poorly for the long tail: a fourteen-room resort in Rizal, a van operator in Quezon province, a community-run island-hopping outfit in Bohol. Global platforms charge commissions that small operators feel, require payment infrastructure many of them lack, and have no physical presence when a trip goes wrong. The second is the social-commerce layer: Facebook pages, TikTok accounts, group chats. This is where much of the actual domestic booking volume lives, and it is fast, cheap and completely unaccredited. The Department of Tourism accredits agencies for a reason — there is recourse when a deposit disappears — but a traveler wiring money to a Facebook page has none. The layer’s success is precisely its risk. The third is the traditional agency layer: walk-in offices, print-quotas, phone calls. This layer owns trust. Travelers know the person behind the counter; the office has a door they can knock on. But its scale is capped by geography and office hours, and its costs are baked into every quote. The fourth is the direct phone-and-cash layer that small suppliers run among themselves. A resort takes reservations by phone and SMS; a van driver’s calendar is his own phone’s message thread. This layer is free to operate and invisible to everyone, which is the problem: a resort that cannot be found online does not exist to the traveler comparing options at ten at night. CieloAmor’s model is an attempt to build the layer that sits on top of all four rather than replacing any of them. The company’s website gives partners — hotels, resorts, tour operators, transport providers — separate accounts to manage their own listings, rates and availability, and charges commission only when a booking is made. The agency’s DOT accreditation attaches to every booking, its published terms put cancellation rules in writing before payment, and its Teresa office gives travelers a door to knock on. Installment payment plans on eligible packages address the single most-cited barrier in the company’s own launch materials: paying in full, upfront, for a trip that is weeks away. Whether this hybrid — digital convenience with accredited accountability behind it — scales beyond Rizal is the open question that the next few years will answer. The external variables now in motion Two forces outside any single company’s control will shape how fast this layer gets built. The first is the source-market shift. China granted Philippine-bound travelers a visa-free stay of up to 14 days in 2026, a policy that helped push Chinese arrivals to 1.74 million in 2019, the pre-pandemic peak, and is now recovering: the first eight months of 2026 recorded 310,088 Chinese visitors on the eTravel caliber, against 303,000 on the count used by Chinese community press. American visitors, the largest market at 818,318 to 926,575 depending on caliber, and South Koreans at roughly 730,000, both skew heavily toward established destinations and bookable inventory. Visa liberalization on both sides of the South China Sea is pushing volume toward destinations — second-tier provinces, nature escapes, domestic carriers — where the digital booking layer is thinnest. The second is the policy framework. The ASEAN strategic plan that Philippine Tourism Secretary Christina Garcia Frasco chaired in Cebu explicitly frames digital integration of travel services as regional policy, alongside green-hotel and clean-city standards that small suppliers will eventually be measured against. The plan’s 8.7% annual growth target is not binding law, but it sets the metric by which every member’s tourism ministry will be judged. For the Philippines, closing the booking gap is the most direct route to closing the growth gap. The counter-example is worth stating plainly. None of these forces guarantees that the accredited-platform model wins. If social commerce continues to grow faster than accredited channels — a plausible outcome, since it is free and requires no paperwork — the trust gap could widen even as the digitalization rate rises. Policy can push supply online; it cannot force travelers to care who is behind the listing. That contest is commercial, not regulatory. Three questions for Julieann Rebanal Your launch statement says travelers “still want someone they can call.” Isn’t that an argument against moving bookings online? It is the opposite. What we heard from travelers, over years of running trips the traditional way, is that the phone call was never the problem. The problem was what came after the call: nothing in writing, a deposit to an account you could not verify, and no way to change the plan without starting over. The website keeps the part people value — a team that answers, an office in Teresa, a DOT accreditation behind every booking — and removes the part they did not sign up for. Our partners get the same thing in reverse: they keep managing their own rates and availability, but now a traveler in Luzon can find them at ten at night without anyone making a phone call. Online booking in this market will not win by being more digital than the phone. It will win by being more accountable than the Facebook page. Installments are your most distinctive feature. Who carries the risk when a traveler pays a package in three parts? The installment plans on eligible packages run directly through our website, and the terms — what happens on cancellation, at what point which portion is refundable — are published before the traveler pays anything. That is deliberate. In the traditional setup, the deposit question is exactly where trust breaks: the operator wants cash upfront, the traveler wants an escape hatch, and both are right. Spreading payment over time changes the calculus on both sides. For the traveler, the trip stops competing with this month’s bills. For our partners, a booking that installs itself over three payments is still a booking they can plan inventory around. We are not inventing consumer credit. We are attaching it, in writing, to a sector that has mostly run on handwritten receipts. You are starting in Luzon and plan nationwide listings through 2027, plus a Manila branch. What decides whether that expansion works? Whether the long tail actually lists. Every platform lives or dies on the small suppliers it was supposed to serve, and our bet is that commission-on-booking removes the reason a small operator says no. There is no listing fee, no monthly charge; the resort in Palawan or the van operator in Rizal pays only when money has already come in. The Manila branch in 2027 matters for the same reason the Teresa office matters now — this market wants a door to knock on. If we do this right, the measurement is simple: more bookings for small Philippine tourism businesses, and a traveler who can compare, pay and reschedule without a single phone call. If the small suppliers do not come online, none of the rest of it matters. What 2027 will decide The pieces now in motion — a regional growth target of 8.7% a year, visa relaxation on both sides, a domestic market whose volume everyone can see and nobody can count — point to the same conclusion. The Philippine travel industry’s next efficiency gain will not come from a new destination or a new airline route. It will come from the unglamorous work of putting the country’s fourteen-room resorts and van operators into bookable, accountable, digital inventory, and attaching consumer payment tools to them. CieloAmor Travel & Tours is one of the first agencies to attempt this from inside the traditional layer rather than outside it — a DOT-accredited office in Teresa, Rizal, that built a website instead of waiting for one to be built for it. Its 2027 plan, Luzon first and nationwide listings with a Manila branch, will be watched less for whether the company succeeds than for what it proves: whether travelers will move from the Facebook page to the accredited listing when the difference is finally visible at checkout. If they do, the phone will not disappear from Philippine travel. It will just stop being the booking engine. Data Basis All quantitative claims in this article trace to the author’s local knowledge base of published tourism statistics. Key figures and their provenance: Philippines international visitors (6.44 million, 2025, incl. balikbayan) and tourism receipts (PHP 694 billion, 2025): Department of Tourism figures as reported by the Central News Agency (Taiwan) and carried by CE.cn. Tourism direct GDP contribution (8.1%) and tourism employment (7.7 million jobs, 2025): Department of Tourism figures as carried by World News (Philippine Chinese-language press). Visitor target (6.6 million, 2026): DOT target as reported by Migrant Times. Cumulative visitor growth (3.46% YoY): Philippine Business News, October 2026. First-eight-months 2026 visitor counts: two paired calibers are cited throughout — eTravel-system-only (4,115,860 total; US 818,318; Korea 727,379; China 310,088) and merged-caliber including balikbayan (4,415,860 total; US 926,575; Korea 744,732), plus a third LPC-community-press count (4.4 million; China 303,000). The 300,000 gap is definitional (whether balikbayan are counted). Cross-caliber comparisons are avoided. ASEAN figures: 144 million arrivals (2025, 29th M-ATM Joint Media Statement); 201 million 2030 forecast, 51% cumulative 2025–2030 growth target and 8.7% CAGR (ASEAN Business Bulletin, second edition, 2026 — no direct URL in the base). Thailand: foreign market revenue THB 1.53 trillion (2025, NBT World); 36.7 million foreign visitor target and 205 million domestic trips target for 2026 (Royal Thai Government portal). Singapore: 16.9 million arrivals (STB via Bernama); SGD 32.8 billion receipts (STB via TTR Weekly); per-visitor receipt of SGD 1,941 is a value derived by the knowledge base from receipts divided by arrivals, not a directly reported figure. China domestic tourism: 6.52 billion trips and CNY 6.3 trillion spending (Ministry of Culture and Tourism, September 2026). Indonesia domestic trips target: 1.25 billion (Travel Daily News Asia). Philippines–China 14-day visa-free stay and the 2019 peak of 1.74 million Chinese visitors: DOT figures via Migrant Times and World News respectively. Global context: 1.52 billion international arrivals and USD 1.9 trillion receipts (UN Tourism Barometer, January 2026); EU tourist accommodation nights of 3.08 billion (Eurostat, January 2026). Limitations 1. Company-sourced facts are not independently verified. CieloAmor’s DOT accreditation, the installment feature, the commission-on-booking model, the January 2027 launch date, the Luzon-first rollout and the 2027 Manila branch all come from the company’s own press release (October 2026). They are described as company statements. 2. Executive quotes are drafted, not verbatim. The Q&A with founder Julieann Rebanal is written from the company’s launch materials and represents what the company would plausibly answer; the company has not confirmed the wording. The one direct quotation in the opening section is from the press release itself. 3. No reliable public data exists on the Philippines’ domestic trip volume, online booking penetration, or the number of DOT-accredited small suppliers online — the article’s central argument therefore rests on documented friction and regional comparison rather than a Philippine digitalization rate. 4. Caliber discipline: Philippine arrival figures appear in at least three published calibers. Where two are cited, both are shown. One visitor figure (LPC caliber, 4.4 million) circulates without a stable URL and is used only in passing. 5. The ASEAN 8.7% CAGR and 51% cumulative target are goals, not outcomes, and are labeled as such. Sources ASEAN Secretariat: Joint Media Statement of the 29th M-ATM (https://asean.org/wp-content/uploads/2026/02/Adopted-JMS-29th-M-ATM.pdf) UN Tourism: World Tourism Barometer, January 2026 (https://pre-webunwto.s3.eu-west-1.amazonaws.com/s3fs-public/2026-01/World_Tourism%20Barometer_Jan26_excerpt_v2.pdf) Eurostat: Tourist accommodation nights reached record 3.08 billion in 2025 (https://ec.europa.eu/eurostat/web/products-eurostat-news/w/ddn-20260116-1) CE.cn / Central News Agency: Philippines tourism figures, DOT data (https://www.ce.cn) World News (Philippines): Philippine tourism GDP and employment figures (https://www.worldnews.ph) Royal Thai Government: Thailand tourism targets (https://www.thaigov.go.th) Singapore MTI: Written reply on tourism and MICE outlook (https://www.mti.gov.sg/newsroom/written-reply-to-pqs-on-outlook-on-singapore-s-tourism-and-mice-sectors-given-middle-east-conflict) Travel Daily News Asia: Indonesia tourism strategy (https://www.traveldailynews.asia/destinations/indonesia-tourism-sector-balances-crisis-management-and-sustainable-growth-strategy/) Ministry of Culture and Tourism, PRC: 2025 domestic tourism data (https://www.mot.gov.cn) CieloAmor Travel & Tours: Company press release, October 2026 (https://cieloamor.com/) About CieloAmor CieloAmor Travel & Tours Inc. is a Department of Tourism (DOT)-accredited travel agency based in Teresa, Rizal, Philippines (https://cieloamor.com/). Portions of the data and interview insights featured in this article were provided by the company; for any related inquiries, please contact CieloAmor Travel & Tours Inc. at Diversion Road Boulevard, Teresa, Rizal, Philippines, via phone at +63 966 993 4266, or by email at support@cieloamor.com.
More
Grab’s Southeast Asia Call: Three Promises Made to Three Different Rooms SeaPRwire

Grab’s Southeast Asia Call: Three Promises Made to Three Different Rooms

Reading Grab’s first-quarter 2026 earnings call line by line: the AI numbers were for investors, the fuel rebates for drivers, the autonomy caution for regulators SeaPRwire – The prepared remarks on Grab’s first-quarter 2026 call run about 1,600 words and never change register. Anthony Tan, the group chief executive, speaks in the same calm cadence whether he is describing a 23% lift in driver earnings per online hour or a regulatory cap that cuts his commission in his largest market. That flatness is the reason the transcript is worth an hour. A single voice, addressing four constituencies in sequence, tells you which number each constituency is expected to accept. The quarter itself was strong on the metrics the company chooses to lead with. Revenue rose 24% to US$955 million. On-demand gross merchandise value reached US$6.1 billion, also up 24%. Adjusted EBITDA climbed 46% to US$154 million and the margin on revenue went from 13.7% to 16.2%. Profit for the period was US$120 million against US$10 million a year earlier. Guidance for the full year was repeated rather than raised, at US$4.04 billion to US$4.10 billion of revenue and US$700 million to US$720 million of adjusted EBITDA. What follows is not a summary of those numbers. It is a reading of where each sentence was aimed, what the company volunteered, and what it left out. The distinction matters because the regulatory story that dominated Indonesian headlines in 2026, an 8% cap on ride-hailing commissions, turns out on Grab’s own disclosure to touch a slice of one market small enough that no analyst on the call asked about it in the portion that was published. What Was Said, and to Whom The call opens with a ritual disclaimer from Douglas Yu, director of investor relations, then hands to Tan for what is effectively a twenty-minute monologue. In that monologue the audience changes four times without any signal that it has changed. First the equity investor, who is told about compounding, about the seventeenth consecutive quarter of adjusted EBITDA growth, about a US$400 million accelerated share repurchase and about a stock price the company calls dislocated. Then the regulator, who is told that autonomous vehicles will arrive “at a pace that reflects the trust communities place in us.” Then the driver, who is told that “the structural health of our driver-partner supply base remains our top priority” and that partners earned over US$15 billion on the platform in 2025, up 19%. Then, briefly, the AI partner and the analyst modelling cloud costs, who are told about tokenisation and a Grab Intelligence layer. Each of those passages is internally consistent. Read together they describe a company that has learned to answer four different questions with four different vocabularies, and to do so without ever letting one vocabulary leak into another. Audience What it was told The number doing the work Equity investors Growth is compounding, capital is returning 17th consecutive quarter of adjusted EBITDA growth Drivers Your earnings are protected, fuel support is real US$15 billion earned by partners in 2025, up 19% Regulators Autonomy will not be rushed 40,000 autonomous kilometres, several thousand paid rides AI and cloud partners The data layer is the moat 20 billion transactions, over 50 million users The Investor Paragraph: AI as an Answer to a Margin Question The most quoted line from the quarter is that drivers who adopted Turbo, the AI driving mode inside the GrabDriver app, saw a 23% uplift in earnings per online hour compared with drivers who did not adopt it. It is a striking figure and it is doing two jobs at once. For a driver it is an argument to switch the feature on. For an investor it is evidence that the AI budget produces revenue rather than only cost. The margin arithmetic is where the two jobs diverge. Adjusted EBITDA margin improved to 16.2% of revenue from 13.7%, an improvement of 2.5 percentage points. Over the same period regional corporate costs rose by US$28 million year on year to US$114 million, a 32.6% increase, which the chief financial officer, Peter Oey, described as capital deployed into AI infrastructure rather than a drift in overhead. That is a large enough increase to invite a question about when the spending stops. Oey’s answer was a flat commitment: he is “not expecting any further step-ups from regional corporate costs” and expects the line to stabilise around the first-quarter level for the rest of 2026. He also gave the adoption numbers that are supposed to justify the spend: more than 50% of drivers using the AI assistant, 1.25 million interactions in two months, roughly half of active single-store merchants on the assistant called Mine, a 15% GMV uplift for engaged merchants, and average advertiser spend up 44%. Whether a 23% earnings uplift for adopters is a platform effect or a selection effect is the question the transcript does not settle. Drivers who opt into an earnings-optimisation tool are plausibly the ones already inclined to optimise. The company reports the comparison as adopters against non-adopters, which is the comparison most favourable to the feature and the one least able to separate the tool from the temperament of the people who choose it. There is a second, quieter figure in the same passage that carries more information than the 23%. Mobility transactions grew 28% year on year while mobility GMV grew more slowly. More trips, less value per trip: that is the signature of a market where riders are trading down, and it is consistent with a region absorbing a fuel shock. Tan acknowledged the shock directly, noting that fuel price volatility emerged in early March and that the company deployed targeted fuel rebates and engaged regulators across its markets. The Driver Paragraph: Fifteen Billion Dollars and a Tracker The driver passage is the most carefully constructed part of the monologue, and it is built to answer a criticism the company does not name. Platforms in Southeast Asia have spent two years being told that their commission take is too high and that driver incomes have not kept pace. Tan’s response is to move the unit of account from commission percentage to aggregate payout. Partners earned over US$15 billion on the platform in 2025, up 19% year on year. That is a gross figure across nine operating territories and it says nothing about hours worked, cost of fuel, vehicle depreciation or the distribution of earnings across drivers. It is also, as a rhetorical object, extremely effective: a 19% increase in aggregate partner earnings is hard to argue with and easy to repeat. The second element is procedural. In April the company launched a Digital Earnings Tracker giving drivers visibility into how a fare is split. A tracker is a concession that does not cost margin. It concedes the demand for transparency while leaving the split itself unchanged, and it arrives in the same quarter as the Indonesian regulation that does change the split, in one segment, by force. The gap between those two instruments is the most interesting thing in the transcript. One is voluntary, national in scope, and produces information. The other is mandatory, confined to two-wheelers, and moves money. The company spent more words on the first. The Regulator Paragraph: Autonomy at the Pace of Trust The autonomy section is written for a reader who is worried. Tan describes the Ai.R service with WeRide, launched in Punggol in April 2026 as the first autonomous passenger service inside a Southeast Asian residential estate, then immediately lowers the temperature. Adoption “remains nascent.” Regulators are taking “a measured approach,” which the company believes is “the right approach for our region.” Then the sentence that the whole section exists to deliver: “To be clear, we do not expect anyone to be able to deploy impactful disruption to our human driver network in the near future.” That sentence is addressed to drivers and to transport ministries at the same time, and it is the only place in the monologue where the company volunteers a limit on its own technology. It sits oddly beside the operating numbers, which show a fleet scaling fivefold between April and September, cumulative autonomous distance rising from 30,000 kilometres at launch to 110,000 by mid-September, unique riders from about 1,000 to more than 12,000, and a 99% recommendation rate. Milestone Fleet Cumulative autonomous km Unique riders 1 April 2026, public launch 10 30,000 1,000+ 29 July 2026, on-demand pilot 10 90,000 9,000+ 14 September 2026, fivefold expansion 50 planned 110,000 12,000+ Scale that against the base. Grab reported 52 million group monthly transacting users in the quarter. Twelve thousand riders is 0.02% of that, and the company’s own target of a few thousand vehicles by 2030 implies a fleet roughly 40 to 60 times the size of the current one. The caution is not false modesty. It is arithmetic stated as policy. The Six Percent That Reframes Indonesia’s Cap Indonesia’s regulation is the largest single regulatory event in Grab’s largest market, and it barely appears in the prepared remarks. The sequence is worth setting out because the sequence is the story. Drivers protested in Surabaya on 28 April 2026. On 1 May, addressing a Labour Day audience reported at 200,000, the government announced a cap cutting the platform commission from about 20% to 8% and lifting the driver share from 80% to 92%. The measure took effect on 1 July. The presidential regulation formalising it, PR 27/2026, was issued on 8 October, five months after the announcement. Then the detail that changes the size of the event. The cap applies only to two-wheeled ride-hailing, the motorcycle taxis known as ojol. Four-wheel ride-hailing and freight are outside it. Grab and GoTo together hold more than 90% of Indonesian ride-hailing, so a cap on commission sounds like a cap on the duopoly’s core revenue. Grab’s own disclosure puts two-wheelers at about 6% of its Indonesian mobility GMV. Six percent of one country’s mobility GMV, at a commission cut of 12 percentage points, is a rounding error against a group that reported US$6.1 billion of on-demand GMV in a single quarter. That is why the cap, which generated weeks of coverage, produced no question in the published portion of the call and no mention in the prepared remarks. The driver organisations understood the distinction before the analysts did. The Indonesian transport workers’ union, SPAI, rejected the 8% settlement in June on the grounds that it covered only GoRide and GrabBike while leaving four-wheel and freight untouched. Its own figures put driver daily income at around 100,000 rupiah against a Jakarta minimum monthly wage of 5.7 million rupiah, which works out to roughly 53% of the minimum for a month of work, before fuel, and an hourly rate near 28% of the minimum wage on shifts of 12 to 18 hours. Element Before After Platform commission about 20% 8% Driver share 80% 92% Scope all ride-hailing two-wheeled passenger only Time from protest to announcement 3 days Time from announcement to regulation 5 months The Incentive Line Is Bigger Than the Regulation Put the two numbers side by side and the scale of the Indonesian intervention becomes clear. Grab spent US$650 million on total incentives in the quarter, equal to 10.5% of on-demand GMV, an increase of 46 basis points year on year. The commission cap moves a 12-point share on the two-wheeled slice of one country’s mobility book. A rough bound is enough to see the order of magnitude. If Indonesia accounted for 30% of Grab’s mobility GMV, and mobility GMV were around US$1.7 billion a quarter, that would put Indonesian mobility at roughly US$510 million. Six percent of that, being two-wheelers, is about US$31 million, and 12 points of commission on it is under US$4 million a quarter. The company has not published the underlying figures, so the estimate is illustrative rather than reported. Even doubled or tripled it does not approach the US$650 million the company chose to spend on incentives in the same three months. That asymmetry explains the calm. A regulator changed the price of one product in one market, and the company absorbed it inside a line item it was already expanding for other reasons. The fuel shock was the larger force: the release attributes the rise in incentives partly to supporting driver earnings “in light of increased fuel costs across the region,” which is a cost the platform pays to keep supply on the road, not a cost imposed by statute. It also explains why the more consequential regulatory question in the transcript is not the cap at all. It is the excise restructuring in Thailand, the purchase subsidies in Indonesia and the local-content conditions spreading across the region, because those determine what vehicle a driver buys and therefore who finances it. Grab’s lease-to-own programme with two Chinese manufacturers exists precisely because the answer to that question has shifted from the bank to the platform. The Region Behind the Call The call is a Singapore-listed company reporting in dollars about a region whose transport transition is running on three clocks at once, and the mismatch explains much of the caution in the language. Electrification is moving by the quarter. Electrified vehicles took 32% of ASEAN-6 sales in the first half of 2026, with Thailand at 206,000 electrified units sold, up 47%, and Chinese brands holding 47% of the electrified segment. Vietnam’s battery-electric share of new passenger cars reached 44% on ICCT’s measure, a figure that conflicts with the 35.3% published by VnExpress on a different denominator, a gap this library has recorded rather than resolved. Autonomy is moving by the year, and mostly inside one residential estate in Singapore. Commission regulation is moving by the day, and in the opposite direction to the company’s interest. Indonesia is not an outlier in intent, only in mechanism. Thailand is restructuring its excise tax to reward local manufacturing rather than imports, with a proposed top tier above 10% and a finance ministry figure of about 30% for fully imported vehicles, two numbers that do not reconcile. Indonesia’s own EV incentives, 100,000 cars and 100,000 motorcycles from June 2026, with a 5 million rupiah subsidy per electric motorcycle and VAT relief of 40% to 100%, are a purchase subsidy layered on top of a commission cap, which means the same government is simultaneously lowering the platform’s revenue per trip and subsidising the asset the platform wants drivers to buy. Grab’s answer to that has been financing rather than ownership. Its lease-to-own arrangement with BYD and GAC, announced in May 2026, targets up to 70,000 vehicles across six countries, filling a gap that banks left because a driver with no credit history and a two-year-old motorcycle is not a lending proposition. The gross loan portfolio reached US$1.44 billion in the quarter, loan disbursals grew 67% to more than US$1 billion for the first time, and financial services are guided to break even on adjusted EBITDA in the second half of 2026. The other transport story in the region runs on a different clock entirely. The Whoosh high-speed line between Jakarta and Bandung marked its third year in October 2026 with 18 million cumulative passengers, 58,666 train services, 8.9 million kilometres of safe operation and a punctuality rate of 99.4%, carrying 142.3 kilometres in 46 minutes at a top speed of 350 kilometres per hour. It is a state-backed piece of infrastructure with a fixed route, and it competes with Grab only at the two ends of the journey. Four Questions the Prepared Remarks Do Not Answer The transcript is unusually long on mechanism and short on four quantities that would settle most of the arguments above. What the 8% cap costs. No figure is given for Indonesian two-wheeler revenue, revenue per trip, or the earnings impact of the 12-point commission cut. The 6% of mobility GMV is the closest the disclosure comes. What a fuel rebate costs. The company says it deployed targeted rebates in March and that incentives rose 46 basis points to 10.5% of on-demand GMV. It does not split that increase between fuel support and competitive spend. What an autonomous ride costs. Distance and rider counts are given; cost per ride, cost per kilometre and the safety-operator ratio per vehicle are not. What the AI spend returns. Adoption rates and uplifts are given for adopters. The counterfactual, meaning what those drivers would have earned without the tool, is not. None of these omissions is improper. A quarterly call is a disclosure event with legal boundaries, and forward-looking unit economics are exactly the kind of number a listed company avoids. The point is narrower: the four numbers that would let a reader judge the quarter are the four numbers the format does not produce, and the four numbers the format does produce are the ones that flatter it. Sourcing note Quotations are taken from Grab’s first-quarter 2026 results release dated 5 May 2026 and from the published transcript of the same day’s call. The transcript available without a subscription covers the prepared remarks and the opening question from the floor; quotations from the later Q&A are not used here. Direct quotations are reproduced as published, including the transcript’s own rendering of names. Figures for autonomous fleet size, cumulative distance and rider counts are from three Grab releases dated 1 April, 29 July and 14 September 2026, which is why they are presented as a series rather than a single snapshot. Indonesian regulatory dates are from the presidential regulation and from contemporaneous reporting. Limitations of This Account Three limits apply. The call transcript used here is a third-party rendering, not the company’s own file, so wording in the Q&A portion may differ from the official version. The 6% two-wheeler share is a company disclosure without a published denominator. And no driver was interviewed for this piece; the earnings figures on driver income come from SPAI, which is an advocacy organisation with an interest in the number being low. Sources Grab — Grab Reports First Quarter 2026 Results, 5 May 2026 Grab Investor Relations — Q1 2026 Earnings Press Release, 5 May 2026 EarningsCall — Grab Holdings Q1 2026 earnings call transcript, 5 May 2026 (third-party rendering of the Grab call) Grab — Grab expands autonomous fleet by fivefold, 14 September 2026 Tech in Asia — Indonesia caps ride-hailing commissions at 8%, October 2026 ANTARA — Indonesia targets June rollout for EV incentives, 12 May 2026 ICCT — The next wave of battery electric car adoption, October 2026 This article was prepared by the expert team at Global Infinity Labs, drawing on insights and data provided through its MCP data services. About Global Infinity Labs Global Infinity Labs is an AI innovation company specializing in MCP data services. Email: support@globalinfinitylabs.com
More
Singapore’s Family Offices Got a Hiring Reprieve. The Outsider Clause Did Not Move SeaPRwire

Singapore’s Family Offices Got a Hiring Reprieve. The Outsider Clause Did Not Move

What MAS circular FDD Cir 05/2026 changed on 1 August 2026, what the 2,000-office count measures, and why the second hire is the hardest one SeaPRwire – The rule is four sentences long and it creates a job. A single family office applying for Singapore’s 13O tax incentive from 1 August 2026 needs one qualifying investment professional at the point of application. It needs two by the end of the first basis period of the award, and at least one of those two must not be a member of the family. Miss the deadline and the award is revoked from its commencement date, which is a retrospective clawback dressed as an administrative deadline. Read that again as a hiring brief rather than a tax condition and a specific person appears: a portfolio manager, research analyst or trader, Singapore tax resident, paid more than S$3,500 a month, substantially engaged in fund management, willing to work for a single family’s vehicle, and structurally unable to be the founder’s son. That person is the subject of this piece. Not the family, not the fund, not the S$6.7 trillion of assets under management that the city-state reports, but the outsider who has to be on the payroll before the first financial year closes. The reason to look at the rule from this end is that every public account of the August change looks at it from the other end. The story told in advisory notes, in client alerts and in the trade press is a story about thresholds coming down. The story told by the circular, read line by line, is a story about a deadline moving and a headcount staying put. The Person the Circular Creates Start with the definition, because the definition is where the difficulty sits. MAS’s FAQs for single family office funds, attached as Annex 11 to the circular, describe an investment professional as a portfolio manager, research analyst or trader who is a Singapore tax resident, earns more than S$3,500 a month and is engaged substantially in fund management. All four elements must hold. The FAQ is explicit that a senior title alone does not qualify, and it lists what does not count: budgeting, capital account management, cash flow monitoring, legal documentation, fund wiring, tax planning support, and keying in or confirming orders. A chief operating officer or a family office controller will not usually count. That definition rules out most of the people a wealthy family already employs. The accountant who has run the family’s books for a decade is not an investment professional. The lawyer who structured the trust is not an investment professional. The principal’s daughter, if she has spent five years in the family’s private investments, might be, which is exactly why the second seat has to be filled by someone who is not her. There is a further constraint that is easy to miss. The investment professional must be employed directly by the fund manager under a formal employment contract exercised in Singapore, and must hold a valid Employment Pass where applicable. For a foreign hire, the pass is the critical path. The qualifying salary for a new Employment Pass in the financial services sector is S$6,200 a month at age 23 and below, rising to S$11,800 at 45 and above, with the thresholds moving to S$6,600 and S$12,700 for applications from 1 January 2027. The COMPASS points framework applies, with an exemption only at a fixed monthly salary of S$22,500 or above. So the brief is not simply “hire an analyst”. It is: hire an experienced investment professional, on a salary well above the statutory floor, who can pass a points-based immigration test, who is willing to work for a single family rather than an institution, and who must be in place by a date set by the fund’s own financial year end. Requirement At application By end of first basis period 13O or 13OA investment professionals 1 2, at least 1 non-family 13U investment professionals 2 3, at least 1 non-family Consequence of missing the deadline none yet award revoked from commencement date Minimum assets under management S$20 million for 13O, S$50 million for 13U, tested at application and each basis period end same How Many of Them, and How Few Exist More than 2,000 single family offices held tax incentives in Singapore as of the end of 2025, according to a written parliamentary reply published by MAS on 5 August 2026, which also reported assets under management rising 10.1% to S$6.7 trillion in 2025. A BCG estimate circulated in May 2026 put the wealth management pool at US$2.1 trillion, up 10.3%, with the same 2,000-plus count. Two thousand offices, each needing at least one non-family investment professional, is a demand figure of at least 2,000 seats, and the true figure is higher because 13U funds need three professionals in total. Set that against a supply side that recruiters describe as thin and getting thinner. The compensation evidence is the clearest signal. A market note published by Asia Capital Notes estimates mid-tier investment professional pay in Singapore, meaning five to ten years of experience with single-asset-class specialisation, rising from a 2022 baseline of US$120,000 to US$180,000 all-in to US$180,000 to US$280,000 in 2026. Senior professionals moved from US$200,000 to US$300,000 up to US$280,000 to US$450,000. The same note estimates that a senior search that took two to four months in 2022 now takes four to nine. Measure 2022 2026 Mid-tier investment professional, all-in US$120,000 to US$180,000 US$180,000 to US$280,000 Senior investment professional, all-in US$200,000 to US$300,000 US$280,000 to US$450,000 Time to fill a senior search 2 to 4 months 4 to 9 months Number of single family offices on incentives below 1,400 at end-2024 more than 2,000 at end-2025 That pay curve is what a binding constraint looks like from the outside. When a candidate pool cannot expand, price does the adjusting. A recruiter quoted in the same note put it plainly: “Senior IP candidates are receiving competing offers 2-3x more often than they were two years ago.” What Everyone Says the Change Means The published commentary on the circular clusters tightly around one sentence, and the sentence is that the threshold has come down. A typical advisory summary explains that the old rules required two investment professionals at application for 13O and three for 13U, that a family office could not proceed if the team was not in place, and that from 1 August 2026 an applicant needs only one, with the rest to follow by the end of the first basis period. Another describes the change as the regulator recognising that “people are hard to hire” in the early stage of a family office, and reframing headcount from a precondition of application into a transitional operating obligation. That framing is accurate as far as it goes. It is also the framing that produces the misunderstanding. A reader who takes “only one at application” as the headline concludes that the requirement has halved. It has not halved. It has moved. One of the advisory notes says so directly, in a sentence that deserves to be the lede of every other note: the new rules relax the standard only at the launch stage, and the final headcount and qualification requirements were not lowered. Another makes the consequence concrete: if the second investment professional is not in place by the deadline, the tax exemption for that basis period cannot apply. There is a second published view worth recording because it pushes back on the hiring story altogether. Walter Ng, director and chief financial officer of Singapore-based Ruifeng Wealth Management, told an industry publication in September 2026 that the difficulty is not volume. “The challenge is not simply having enough people, but having professionals with the right combination of expertise, experience and adaptability to keep pace with a fast-changing environment,” he said, adding that “there is no one-size-fits-all approach” as family offices take on governance, succession, tax and legal work alongside portfolios. Ng’s point is a useful corrective to the numbers above. A market can have 2,000 vacancies and still fail to fill them, not because too few people exist but because the job has quietly become broader than the title. Which Link in the Chain Produces This The outcome that puzzles families is specific: they have the money, they have the structure, they have the tax incentive, and they cannot get the second name on the organisational chart. Tracing the chain shows why the difficulty is structural rather than personal. The first link is the definition. Investment professional is a narrow category defined by function, not seniority. Most of the experienced people a family already trusts sit outside it. The second link is immigration. A non-family hire is usually a foreign hire, and a foreign hire needs an Employment Pass at financial services salary thresholds, scored under COMPASS, with the pass processed in about ten business days and an in-principle approval valid for six months. Add search time of four to nine months and the calendar is decided before the candidate is. The third link is the calendar itself. The deadline is the end of the first basis period, which is set by the fund’s own financial year end, not by a date the family chooses after the fact. A fund with an August 2026 start and a December year end has roughly five months to complete a search that the market says takes four to nine. The fourth link is the one nobody advertises. The clause requires at least one investment professional who is not a family member. For a family whose entire investment capability is familial, that is not a hiring problem, it is a governance problem: the office must import a stranger into the decision-making layer, with the authority the title implies, in order to keep a tax exemption. What counts as an investment professional What does not Portfolio manager Chief operating officer Research analyst issuing buy or sell recommendations Family office controller Trader, including liquidity management and deal structuring Staff doing budgeting or cash flow monitoring Singapore tax resident earning above S$3,500 a month Anyone whose title is senior but whose function is administrative Who Cannot See This Link The interesting question is not why hiring is hard. It is why so many families discover the difficulty late. The principal sees a tax incentive. The advisory layer sees a threshold. The marketing material that circulates in the family office world sees a jurisdiction becoming easier to enter. Each of those views is correct within its own frame, and none of them is the frame that contains the deadline. The deadline sits in the operational layer, which is precisely the layer a newly established single family office does not yet have. Before the second investment professional is hired, there is no one whose job it is to track the basis period. The compliance calendar is administered by the same small team that is short of a member. There is a public number that captures the resulting mismatch. An Ocorian survey cited in industry commentary reports that 61% of family offices say they have difficulty recruiting and retaining qualified investment professionals, with average chief investment officer pay in Singapore and Hong Kong above S$400,000 to S$550,000. That is a market describing its own tightness while continuing to advertise itself as open. The visibility problem compounds itself across a portfolio. A family with one Singapore vehicle and one elsewhere can see both tax positions. It cannot see that the two vehicles now compete for the same narrow pool of candidates, that the deadline for each is set by a different financial year end, and that the person who satisfies one is often the person the other needs. The clause is written per fund. The labour market it draws on is not. What the Reprieve Costs Over Three Years The headline saving is real and it is smaller than it looks. Deferring one hire by a few months removes a few months of salary from the first year, which at the market rates above is somewhere between S$60,000 and S$120,000 of cash timing. Against the cost of maintaining the structure, that is not the number that decides whether the office works. Three conditions do more work. The first is assets under management. A 13O single family office fund must report S$20 million of designated investments at application and maintain it at each basis period end. A 13U fund must report S$50 million. The circular simplifies when this is tested, not what it is. The second is local business spending, which the circular now tiers by assets under management: S$200,000 a year below S$250 million, S$500,000 between S$250 million and S$2 billion, and S$1 million above S$2 billion. The third is capital deployment, which stays at 10% of designated investments or S$10 million, whichever is lower, with a multiplier of two for qualifying investments in Singapore-listed equities and in Singapore operating companies. Add those up and the arithmetic of the reprieve changes shape. A family that saves six months of one salary may be spending S$200,000 a year on local business costs and holding S$20 million in designated investments to qualify, while the constraint that actually binds is the second name on the org chart. The circular has moved the cheapest condition and left the expensive ones where they were. There is a further wrinkle that the advisory notes mention and then drop. Economic conditions are tested basis period by basis period. Failing one period does not necessarily end the award; it means the exemption does not apply for that period, and can resume if the following period passes. Non-economic failures are treated differently. For those, including a failure to provide supporting documents or a serious breach, the regulator retains the power to revoke the award permanently. The deadline for the second hire is an economic condition, which is the softer of the two categories, and softer is not the same as optional. Why the Regulator Moved the Deadline Instead of the Headcount The obvious reading of the August circular is that Singapore blinked. The less obvious reading is that the regulator separated two things it had previously bundled: the moment a fund must prove it exists, and the moment it must prove it is staffed. The sequence behind that separation is visible in the public record. The framework was reshaped after the money laundering case that ran through 2025 and pushed the city-state into a broad review of how family office money arrives and who controls it. The April 2026 changes reported at the time tightened the entry conditions. The August circular loosened the timing of the staffing condition while widening scrutiny of the source of funds. A regulator that wanted to reduce the number of family offices would not have relaxed anything. A regulator that wanted the ones already admitted to be verifiable would relax the timing and keep the headcount. That is also why the relaxation is narrow. It does not touch the definition of an investment professional, the non-family requirement, the asset thresholds or the capital deployment condition. It touches the calendar. Read as a single instrument, the circular says the applicant does not have to arrive complete, but must become complete inside the first accounting year, and must be able to show the paperwork for both. For a family deciding whether to set up in Singapore in 2027, that is a more useful signal than either the alarmist or the promotional reading. The door is not narrower. The inspection at the door has moved inside, to a room the family has to build. What the Circular Does Not Say Three questions are left open, and each of them matters more to a family than the headline change. What happens when the second professional leaves. The circular addresses failure to reach the headcount, not failure to keep it. Whether a departure in year three revokes the exemption for that basis period is a question the text does not answer on its face. How substance is verified. The FAQ sets out the function test. It does not set out an inspection regime, and a family office with two people whose job descriptions satisfy the test but whose actual work is portfolio reporting for one beneficiary has a compliance question the document does not resolve. Whether the relaxed application standard changes the economics. Cheaper entry, same endpoint, higher salary market. The circular reduces the cash needed at month one and leaves the steady-state cost where the market has put it. There is a fourth question that is not legal at all. If the point of the outsider clause is to import independent judgement into a family’s investment decisions, and if the outsider is selected primarily for the ability to satisfy a deadline, the clause produces a name on a contract. Whether it produces judgement is a question no circular can settle. Sourcing and ethics note All quotations are from published sources: MAS’s written parliamentary reply of 5 August 2026, MAS circular FDD Cir 05/2026 of 31 July 2026 as summarised in professional commentary, MAS’s FAQ material reproduced in that commentary, an industry interview with Walter Ng published in September 2026, and a market note on family office hiring published by Asia Capital Notes. No family office principal, investment professional or regulator was interviewed for this piece, and no composite or invented character is used. The recruiter quotation is reproduced as published, without a name, because the source published it without one. Compensation figures are the note’s own estimates from recruiter commentary, not a published survey, and are presented as such. Where advisory notes disagree about the direction of the change, both positions are given rather than one being selected. Limitations of the Evidence Three limits apply. The circular’s text is quoted through professional summaries rather than the gazetted document, so wording may differ from the original. The 2,000-office figure counts funds holding tax incentives, not all single family offices in Singapore. And compensation estimates rest on recruiter commentary, which is interested in the number being high. Sources Monetary Authority of Singapore — Written reply on single family offices, 5 August 2026 VCC Singapore — MAS FDD Cir 05/2026 summarised: SFO tax incentive changes from August 2026 VCC Act — Family office Singapore Employment Pass: the investment professionals 13O and 13U require, 17 October 2026 Asia Capital Notes — The family office hiring squeeze: investment professional headcount as Asia’s bottleneck NewFortuneTimes — Singapore’s family office boom puts talent in the spotlight, 9 September 2026 BCG estimate reported by JW View — Singapore wealth management at US$2.1 trillion in 2025, May 2026 (citing BCG data) Monetary Authority of Singapore — Family office scheme overview, site home This article was prepared by the expert team at Global Infinity Labs, drawing on insights and data provided through its MCP data services. About Global Infinity Labs Global Infinity Labs is an AI innovation company specializing in MCP data services. Email: support@globalinfinitylabs.com
More
Saudi Arabia’s HUMAIN Signed the Deals. The Switchgear Decides What Runs SeaPRwire

Saudi Arabia’s HUMAIN Signed the Deals. The Switchgear Decides What Runs

Inside eighteen months of announcements, the 467 megawatts actually live against a 3.4 gigawatt plan, and the grid equipment that sets the real schedule AsiaPresswire – At LEAP 2026, which ran in Riyadh from 31 August to 3 September, HUMAIN disclosed project agreements worth more than US$15 billion. The list ran the length of the stack: AMD for chips, AWS for a cloud region, Microsoft for a distribution channel for an Arabic model, Qualcomm for an end device, Adobe as the first foreign tenant on locally hosted compute, Together AI for 250 megawatts, Applied Intuition for autonomous trucks, SLB for oilfield data. A single company, eighteen months old in its current form, signed across power, silicon, models and applications in four days. That is the action. Everything interesting about Saudi Arabia’s artificial intelligence programme follows from what happened next, which is the part the announcements do not cover. The country had 68 megawatts of data centre capacity in 2021. By the first quarter of 2026 it had more than 467 megawatts, according to the Saudi Press Agency. A report from the commercial office in Jeddah put the count at 60 data centres by the second quarter of 2026, with planned capacity of 3.4 gigawatts. Read those two numbers together and the shape of the problem becomes visible. Roughly 467 megawatts exist. Roughly 3.4 gigawatts are planned. The ratio between them is the story, and it is a story about transformers, switchgear and cooling water rather than about capital. The Action, and the Size of It HUMAIN is owned entirely by the Public Investment Fund, the sovereign fund usually described as holding around US$930 billion, and it sits inside the Crown Prince’s office rather than under a ministry. Its chief executive is Tareq Amin, who ran Rakuten Symphony and before that built a multi-vendor telecom cloud platform at scale. The hire is a statement about what the company is for. It is an operator, not a research lab. The pace it has set is unusual even by Gulf standards. Eleven data centres, capacity coming online at roughly 50 megawatts a quarter, an AWS region promised for December 2026 and a Microsoft region for November 2026, and what the company describes as the first xAI facility outside the United States at 50 megawatts scaling to 500. Amin’s own formulation, quoted in regional coverage, is that the objective is to build in 2026 the equivalent of what Saudi Arabia built in twenty years. The ambition is not the interesting part. The interesting part is that HUMAIN chose vertical integration when the obvious alternative was available. The comparison that regional analysts keep drawing is with G42 in the United Arab Emirates, which restructured around Microsoft’s equity position, aligned itself with the OpenAI and SoftBank Stargate programme, and leases a substantial share of the capacity it sells. HUMAIN owns the data centres, contracts the chips, hosts the models and runs an Arabic consumer product. That is a harder business to execute and an easier one to point at as sovereign. Fourteen Months, Ten Signatures The behaviour sequence is where a profile earns its keep. HUMAIN did not announce a strategy and then execute it. It signed in a specific order, and the order reveals what it thought it lacked at each stage. Date Action What it secured November 2025 US-Saudi Investment Forum framework with xAI More than 500 megawatts of dedicated capacity, plus a US$3 billion stake in xAI’s Series E December 2025 Joint venture with stc through center3 A structure rated to 1 gigawatt, HUMAIN holding 51% January 2026 Non-binding financing framework with the National Infrastructure Fund, signed at Davos Up to US$1.2 billion for a first 250 megawatt wave at Riyadh and Dammam February 2026 xAI Series E closes The equity position becomes real rather than announced April 2026 Legal documentation moves to final drafting The financing converts from framework to contract August to September 2026 LEAP 2026 More than US$15 billion across AMD, AWS, Microsoft, Qualcomm, Adobe, Together AI, SLB and Applied Intuition November 2026 Microsoft cloud region due A hyperscaler anchor inside the Kingdom December 2026 AWS cloud region due A second hyperscaler anchor, on a US$5.3 billion buildout Read down the first column and a pattern appears. The first four moves are about securing power, capital and a partner with an existing grid footprint. The fifth and sixth are about turning commitments into assets. Only then does the company go shopping for silicon and applications. That sequence is not the sequence a software company would choose. It is the sequence a utility would choose. Why Build the Whole Stack Instead of Renting It The case for vertical integration is a case about who captures the margin when compute becomes a tradable commodity, and it rests on three claims that HUMAIN makes explicitly. The first is that sovereign buyers will pay for provenance. A Saudi ministry procuring an Arabic model does not need it to be the best Arabic model in the world. It needs it to be the best Arabic model it can buy on infrastructure inside the country, with evaluation evidence and a documented human-in-the-loop layer. HUMAIN inherited the ALLaM family from SDAIA and has been extending it: broader dialect coverage, a Modern Standard Arabic alignment pass, a Gulf-specific retrieval layer, and a clinical evaluation track aimed at health procurement. The second is that the model layer and the compute layer reinforce each other when both are owned. HUMAIN unveiled a 428 billion parameter Arabic model built with China’s MiniMax, trained on more than a trillion Arabic tokens and released as a research preview through its own platform. A model that runs on someone else’s cloud is a customer. A model that runs on your own cloud is a product you can bundle. The third is distribution. The Microsoft arrangement puts ALLaM inside Microsoft 365 Copilot and on the Microsoft Foundry platform, which gives the model a channel it could not build. The AWS arrangement puts ALLaM on Amazon Bedrock and HUMAIN’s compute fabric on the AWS Marketplace. In both cases the sovereign operator trades exclusivity for reach. There is a cost to that choice, and it is concentration. A company that owns the data centres, contracts the chips, trains the models and sells the applications has four execution risks correlated with each other. If the grid slips, the chips sit in crates, the models have nowhere to train and the applications have nothing to run on. The Gap Between Signed and Switched On The gap is quantified in public. Saudi Arabia reported 467 megawatts of operational capacity in the first quarter of 2026 against a planned 3.4 gigawatts. HUMAIN’s own disclosed footprint targets 500 megawatts of AI factory capacity across three clusters, one in Riyadh on PIF land, one at NEOM where the giga-project has already built grid capacity and water-cooling assumptions, and one in the Eastern Province close to Aramco’s industrial backbone. Measure Figure Status National data centre capacity, 2021 68 MW operational then National data centre capacity, Q1 2026 more than 467 MW operational National planned capacity, Q2 2026 3.4 GW planned HUMAIN target footprint 500 MW across three clusters in build HUMAIN and stc joint venture rated to 1 GW structure agreed DataVolt at NEOM Oxagon 100 MW of a 360 MW first phase, 1.5 GW campus construction started xAI capacity in the Kingdom 50 MW scaling to 500 MW announced Capacity added per quarter about 50 MW company statement The arithmetic is unforgiving. To reach 3.4 gigawatts from 467 megawatts means adding roughly 2.9 gigawatts, which at 50 megawatts a quarter is 58 quarters, or more than fourteen years. Even if the quarterly run rate triples, the plan is a decade-long build. The 2030 date that appears in most Saudi AI commentary therefore describes a much smaller number than the headline plan implies, and the honest reading is that the plan is a ceiling rather than a forecast. There is a second way to read the same gap, and it is more generous. A gigawatt of planned capacity is not a promise to build a gigawatt. It is a statement that land, grid applications and environmental approvals have been assembled for that quantity, which is a different asset from a building with servers in it. On that reading the 3.4 gigawatts is a pipeline of options, and the 467 megawatts is the part that has been converted. Both readings support the same conclusion about timing: what exists is a small fraction of what is discussed, and the rate of conversion is the variable that decides whether the Kingdom becomes a compute exporter or a compute importer with good marketing. The announced pipeline also has an internal consistency problem that is rarely stated. HUMAIN’s 500 megawatt footprint, the 1 gigawatt stc joint venture, the 1.5 gigawatt DataVolt campus at Oxagon and the 500 megawatt xAI commitment are not additive in any simple sense, because several of them describe the same physical capacity under different commercial arrangements. A joint venture rated to 1 gigawatt does not create 1 gigawatt on top of a 500 megawatt target. It describes who owns the meter. What the Structure Cannot Do Four constraints do the real work of setting the timetable, and none of them is capital. The first is high-voltage equipment. Long-lead switchgear and transformer capacity are the operational chokepoint in every Gulf build, and the procurement response has been to buy them the way the company buys GPUs: on multi-year commitments rather than spot orders. That solves availability for the buyer who moves first and makes the constraint worse for everyone else. The second is cooling water. A 500 megawatt campus consumes water at a scale that has to be contracted before construction, not after. NEOM’s advantage is that the giga-project already modelled water for The Line and can extend those assumptions. The Riyadh and Dammam sites have to negotiate their own. The third is people. The SAMAI programme targets 100,000 AI specialists by 2030. The global pool of engineers who have actually operated a 100,000 GPU cluster is small, and HUMAIN is competing for it against US hyperscalers and against G42. Amin’s hiring has tilted deliberately toward operations and infrastructure engineers rather than model researchers, which is the right tilt for a company whose job is to run AI factories rather than invent them. The fourth is silicon access. The November 2025 export framework and a reported approval for 35,000 advanced accelerators against a pipeline of 600,000 define how fast the compute can arrive. A framework is not a shipment. The gap between the two numbers is the gap between the political relationship and the physical build. The Man Who Runs It Amin’s public statements are worth reading as a set because they are unusually specific about what he thinks the company is not. He has described Saudi Arabia as positioning itself as the “third pillar” of global AI infrastructure alongside the United States and China, and said the commitment to developing compute capacity in the US secures HUMAIN “a strategic foothold”. He has also said that “Saudi Arabia will be the first country outside the US and China that will commercialise its own operating system”, which is a claim about software, not about megawatts, and it is the more falsifiable of the two. An operating system layer above raw compute is exactly what a national champion would want and exactly what is hardest to ship. The operating claim that matters most is the one about speed: building in 2026 what the country built in twenty years. That is measurable. The measure is the gigawatt count of operational, not announced, capacity, and the second measure is whether the announced offtake materialises. HUMAIN says its NVIDIA Blackwell Ultra cloud is already running government and enterprise workloads with utilisation above 90% and the Ministry of Commerce among the first disclosed users. If that utilisation figure holds as capacity triples, the demand thesis is real. If it falls, the build was a real estate programme with a press release attached. The Money, and Where It Comes From The capital stack is worth laying out because it explains why the build has not slowed despite the absence of a commercial customer base large enough to justify it. Source Amount Instrument Public Investment Fund 100% of equity sovereign balance sheet National Infrastructure Fund up to US$1.2 billion non-binding financing framework signed at Davos, January 2026 stc through center3 joint venture rated to 1 gigawatt, HUMAIN 51% and stc 49% corporate joint venture xAI Series E US$3 billion equity stake in the model company Fund managed by BSF Capital initial US$2.5 billion for 250 megawatts with Al Moammar, potentially scaling to 1 gigawatt infrastructure fund HUMAIN venture vehicle US$10 billion target, possibly above technology fund Two things stand out. The first is that most of this is not project finance in the ordinary sense. A conventional data centre developer raises against contracted offtake, and the lenders underwrite the tenants. Here the sovereign underwrites the developer, and the tenants include ministries. The credit being priced is closer to a sovereign than to a colocation operator, which is precisely how the Kingdom intends to compete on cost of capital against US hyperscale builders. The second is the number of instruments. Equity, a national infrastructure fund, a telecom joint venture, a stake in a model company, a third-party infrastructure fund and a venture arm are six different ways of moving money into the same build. That diversification is a hedge against any single channel stalling, and it is also a fragmentation risk: six instruments mean six sets of terms, six reporting lines and six sets of people who believe they own the schedule. The spending commitment attached to the venture arm has a condition that is easy to miss. Investments are tied to portfolio companies using Saudi compute or bringing staff into the Kingdom. That is a sovereign fund using its chequebook to manufacture demand for the asset it is simultaneously building. It is a coherent strategy and an unusual one: most venture programmes invest to make money, this one invests to fill a data centre. What the Neighbours Are Doing The Saudi build is easier to judge against the region than in isolation, because the region is running the same play at different speeds with different degrees of vertical integration. The clearest contrast is with the United Arab Emirates. G42 restructured around Microsoft’s equity position and aligned itself with the Stargate programme, leasing a significant share of the capacity it sells. That trades autonomy for velocity. The Saudi model trades simplicity for control. The capital comparison favours the UAE on distributed commitments, with Stargate sized at US$500 billion globally and a US$1.4 trillion pledge of investment in the United States over a decade, while Saudi capital is concentrated domestically, at roughly US$77 billion through HUMAIN. The second contrast is less obvious and more instructive. Thailand’s Board of Investment reported investment applications breaking 1 trillion baht in the first quarter of 2026, with the digital industry at 873.7 billion baht and data centres accounting for close to nine tenths of that. Thailand is not building a national AI champion. It is processing applications from companies that want to build, using an existing industrial base, an existing grid and an existing regulatory pathway. That difference defines the wager. Saudi Arabia is attempting to build the operator and the infrastructure at the same time, which is why its announcements are larger and its operational megawatts smaller. Thailand is letting other people’s operators build on infrastructure it already has, which is why its application numbers look strong and its sovereign AI story does not exist. Both approaches can work. Only one of them produces a company called HUMAIN. What Would Prove the Thesis Three indicators would settle the argument within eighteen months, and all three are public. Operational megawatts, not announced megawatts. The company discloses capacity additions quarterly. The number that matters is the one that appears in grid interconnection records, not in conference decks. Utilisation on the live cloud. A figure above 90% on a small base is easy. The test is whether it survives a fivefold increase in supply. Arabic workload routing. ALLaM inside Microsoft 365 Copilot and on Amazon Bedrock will show, in usage data, whether sovereign Arabic models win on Saudi infrastructure or become a compliance checkbox in a catalogue of American and Chinese alternatives. There is a fourth indicator that is harder to read but more decisive. Saudi Arabia’s advantage in this race is land, a domestic market of 33 million people roughly three times the size of the UAE’s, and cheaper electricity. Its disadvantage is that hyperscaler relationships and regulatory speed were built elsewhere first. If EMEA and South Asia inference traffic routes through the Gulf, it will route through one hub predominantly. The hub that delivers lower latency, more reliable capacity and better commercial terms takes the traffic, and the terms are set by whoever has spare megawatts first. That is why the switchgear matters more than the signing ceremony. A company can announce US$15 billion of agreements in four days. It cannot compress the lead time on a transformer. Data basis Capacity figures are from the Saudi Press Agency report of August 2026 and from the commercial office report of June 2026, which give 467 megawatts operational and a 3.4 gigawatt national plan respectively; the 2021 baseline of 68 megawatts is from the same SPA report. Deal values and capacities are from the LEAP 2026 summary published by the Chinese Ministry of Commerce’s Saudi office, cross-read against trade coverage of the same announcements. The 50 megawatts per quarter run rate, the 500 megawatt target footprint and the 1 gigawatt joint venture rating are company statements reported in regional and industry press. The financing framework of up to US$1.2 billion is non-binding as described in April 2026 coverage, and is treated here as a framework rather than as funds deployed. Estimates of the time required to reach 3.4 gigawatts are arithmetic performed on the published figures, not company guidance. Limitations of the Record Three limits apply. Announced capacity and operational capacity are reported by different parties on different timetables, so the gap described here is indicative rather than audited. No HUMAIN executive was interviewed; quotations are from published remarks. And the utilisation figure of above 90% is a company claim without a published measurement method. Sources Saudi Press Agency — Saudi data centre capacity from 68 MW in 2021 to more than 467 MW in Q1 2026, August 2026 MOFCOM Saudi office — Overview of LEAP 2026 outcomes, September 2026 FWDstart — The AI announcements from LEAP 2026 worth knowing, September 2026 AI in Arabia — HUMAIN in 2026: anatomy of Saudi Arabia’s sovereign AI champion, 17 May 2026 AI in Arabia — HUMAIN lines up US$1.2 billion for 250 MW, 28 April 2026 Saudi Compute — Sovereign AI in Saudi Arabia: the model versus the UAE model Thailand Board of Investment — Investment applications in Q1 2026 pass 1 trillion baht, 29 April 2026 This article was prepared by the expert team at Global Infinity Labs, drawing on insights and data provided through its MCP data services. About Global Infinity Labs Global Infinity Labs is an AI innovation company specializing in MCP data services. Email: support@globalinfinitylabs.com
More
Five Things German Firms Believe About the AI Act, and What the Text Says SeaPRwire

Five Things German Firms Believe About the AI Act, and What the Text Says

Checking the claims that circulate in German boardrooms against Regulation 2024/1689, the Digital Omnibus in force since 27 July 2026, and the KI-MIG AsiaPresswire – The claim arrives in the same shape every time. A German Mittelstand manufacturer asks its lawyers whether the new European rules apply to the scheduling tool it has been running since 2023, and someone in the room says the high-risk obligations start in August 2026. That sentence was correct for about eighteen months. It stopped being correct on 27 July 2026, when the Digital Omnibus entered into force, and a remarkable number of documents produced after that date still say it. This is not a story about companies being careless. It is a story about a regulatory calendar that moved twice, in two instruments, administered by two levels of government, reported by an industry of advisors whose published output is not versioned. The result is that five specific beliefs are now widespread among German firms, each of them was defensible at some point, and each of them is wrong in a way that changes what a company should do this quarter. The Claim List, With Its Sources Each of the five below is stated in the form it circulates, with the kind of source that carries it. None of the sources is disreputable. Several are law firm publications. The claim as heard Where it comes from What the text says High-risk obligations begin on 2 August 2026 Pre-Omnibus summaries of Article 113 Annex III high-risk moved to 2 December 2027, Annex I to 2 August 2028 Nothing is enforceable until the high-risk rules apply A reading of the Act as one commencement Prohibitions and AI literacy since February 2025, GPAI since August 2025, Article 50 since August 2026 The maximum fine is 35 million euros The headline tier in Article 99 Three tiers, and most obligations sit in the 15 million tier Germany diluted the Act Confusion between the EU regulation and the national implementing law The KI-MIG implements; it does not amend The delay means Brussels caved Coverage of the May 2026 trilogue The delay replaced a standards-linked trigger with fixed dates Myth One: The High-Risk Rules Start in August 2026 This was true. Regulation (EU) 2024/1689 set 2 August 2026 for the high-risk obligations covering stand-alone systems listed in Annex III, the category that includes recruitment, credit scoring, education and biometrics. Then the Digital Omnibus on AI, adopted as Regulation (EU) 2026/1744, entered into force on 27 July 2026 and moved them. The new dates are 2 December 2027 for Annex III systems and 2 August 2028 for high-risk AI embedded in products regulated under Annex I, which covers machinery, medical devices and toys. The Omnibus did not weaken what the requirements demand. It moved when they become enforceable. The detail that matters for a firm planning its year is not the deadline. It is that the deadline is now fixed rather than conditional. The Commission’s original proposal linked application to the availability of harmonised standards, which could have produced an open-ended postponement. Both the Parliament and the Council rejected that mechanism and replaced it with dates. A company that was waiting for standards now has a date it can plan against, and the planning horizon is roughly fourteen months. Myth Two: Nothing Is Enforceable Until 2027 This one is the most consequential of the five, because it converts a postponement into a holiday. Four sets of obligations already apply in Germany. The prohibitions in Article 5 and the AI literacy duty in Article 4 have applied since 2 February 2025. The obligations for providers of general-purpose AI models in Chapter V have applied since 2 August 2025, together with the governance structure and the penalty framework. Article 50 transparency, covering chatbot disclosure and the labelling of synthetic content, has applied since 2 August 2026. And the German enforcement architecture has been live since 29 July 2026, when the KI-MIG entered into force. The Article 5 list is where a German company is most likely to be exposed without knowing it. It bans biometric categorisation using sensitive characteristics outside narrow exceptions, real-time remote biometric identification in publicly accessible spaces outside the law enforcement carve-outs, social scoring, and manipulation of people by exploiting vulnerabilities. A retailer using emotion recognition on customers, a logistics firm scoring warehouse staff, an HR platform inferring health status: all of those sit in territory that has been enforceable for more than a year. There is a further item that lands inside the planning window. The Omnibus added a prohibition on systems generating child sexual abuse material or non-consensual intimate imagery, where that output is a reasonably foreseeable result and the system lacks adequate safeguards. It carries the top penalty tier and applies from 2 December 2026. Date What applies Basis 2 February 2025 Article 5 prohibitions, Article 4 AI literacy Article 113 2 August 2025 General-purpose AI model obligations, governance, penalties Article 113 29 July 2026 German KI-MIG in force, Bundesnetzagentur powers National law 2 August 2026 Article 50 transparency, chatbot and deepfake disclosure Article 113 2 December 2026 New prohibition on abusive synthetic imagery, end of marking grace period Regulation 2026/1744 2 December 2027 Annex III high-risk systems Article 113 as amended 2 August 2028 High-risk AI in Annex I products Article 113 as amended Myth Three: The Fine Is Thirty-Five Million Euros The 35 million euro figure is the one that travels, and it is real. It is also the top of three tiers and it applies to a narrow set of violations. Article 99 sets 35 million euros or 7% of total worldwide annual turnover, whichever is higher, for breaches of the Article 5 prohibitions. It sets 15 million euros or 3% for non-compliance with most other obligations, which includes the high-risk requirements in Articles 9 to 15, the provider obligations in Article 16, the deployer obligations in Article 26 and the Article 50 transparency duties. It sets 7.5 million euros or 1% for supplying incorrect, incomplete or misleading information to notified bodies or authorities. For small and medium enterprises, Article 99(6) caps the fine at the lower of the fixed amount or the percentage. A German company with 20 million euros of turnover cannot face a 15 million euro fine for a high-risk breach, because 3% of 20 million is 600,000 euros, and that is the ceiling. German procedural breaches under the KI-MIG carry separate domestic penalties in the tens of thousands. Tier Maximum Trigger One 35 million euros or 7% of global turnover Breach of an Article 5 prohibition Two 15 million euros or 3% High-risk requirements, provider and deployer duties, Article 50 Three 7.5 million euros or 1% Incorrect or misleading information to authorities SME cap The lower of the fixed amount or the percentage Article 99(6) The practical point is not that penalties are lower than advertised. It is that the tier a company lands in is determined by which obligation it breached, and most of the obligations a mid-sized German firm will actually touch sit in tier two or below. Myth Four: Germany Watered It Down Germany did the opposite of diluting, and the confusion comes from conflating two different instruments. The AI Act is a regulation. It applies directly in all member states without transposition. What member states must do is designate competent authorities, build market surveillance structures and set national penalty procedures. Germany did that with the KI-Marktüberwachungs- und Innovationsförderungsgesetz, the KI-MIG, adopted by the Bundestag on 11 June 2026 and in force from 29 July 2026. The design is deliberate and it is described in German policy circles as lean supervision. Instead of adding national requirements on top of the European ones, Germany routed enforcement through existing regulators. The Bundesnetzagentur in Bonn is the central market surveillance authority and the single national point of contact with the European AI Office. BaFin keeps financial-sector AI. The state media regulators keep transparency rules affecting journalism and deepfakes. A new competence centre inside the Bundesnetzagentur, known as KoKIVO, is meant to support the other regulators. The agency added 43 posts to staff the function. Whether lean supervision is adequate is a fair argument. A regulator that coordinates rather than duplicates depends on the sector regulators having the technical capacity to assess models, and BaFin’s expertise is in prudential supervision, not in machine learning. But that is a criticism of implementation, not evidence of dilution, and the distinction matters because a company that believes the rules were weakened will under-prepare. What the design does give a mid-sized firm is an unusually clear first contact point. The Bundesnetzagentur runs a KI-Service Desk for questions about classification and obligations, and publishes an online Compliance Kompass that walks a user through whether a system is high-risk and which duties follow. Both existed before the KI-MIG and both are free. For a manufacturer with one AI feature and no compliance department, that is a more useful resource than a law firm memo, and almost none of the firms that repeat the five claims above have used it. Myth Five: The Delay Means Brussels Caved The delay is real, and the reason for it is more uncomfortable than the lobbying story. As of June 2026, nine of the 27 member states had formally designated their competent authorities under the AI Act, against a deadline of 2 August 2025. The Commission missed its own deadline for the guidelines on high-risk classification under Article 6, publishing a draft of 148 pages on 19 May 2026 with consultation running to 23 June, months late and still not final. Standardisation bodies had not delivered the harmonised standards the original timetable assumed. A regime that requires conformity assessment, notified bodies and market surveillance cannot start on time if the bodies that perform conformity assessment have not been notified and the standards against which conformity is assessed do not exist. The postponement is not a concession to industry. It is an admission that the infrastructure the Act depends on was not built. That reading has a practical consequence that the lobbying reading does not. If the constraint was institutional capacity, the constraint does not disappear in December 2027. It either gets fixed or the date moves again. A company planning to be ready by the new deadline is making a bet on the Commission and the member states solving a coordination problem they have already failed once. What a German Firm Should Have Filed Already Strip away the calendar argument and the operative question is smaller: what documentation should exist in a German company’s files today, given that four sets of obligations are live? The first is an inventory. The Act does not require an AI register as such, and companies often read that as relief. It is not, because without a list of systems and of the role the company plays in each, there is no way to show which obligations attach. Provider status follows whoever places a system on the market under its own name, which catches more firms than expect it: a manufacturer that ships a predictive maintenance module under its own brand is a provider, not a deployer. A list of every AI system in use, with the vendor, the version and the date it entered service. For each one, the role: provider, deployer, importer or distributor. For each one, a screen against Article 5, recorded even when the answer is negative. For each one, a screen against Article 50, covering chatbot disclosure and the labelling of synthetic content. Records of AI literacy measures, which Article 4 requires and which most firms have never documented. The second is the interaction between the AI Act and the GDPR, which German companies tend to run as two separate workstreams and which the regulators do not. A public body deploying an AI tool to assess eligibility for a benefit needs a data protection impact assessment under Article 35 and, where the conditions are met, a fundamental rights impact assessment under Article 27. The two share most of their factual base. Running them separately doubles the work and produces two documents that can contradict each other. The third is records. Article 12 requires record-keeping for high-risk systems. Article 22 of the GDPR governs automated decision-making and the right to meaningful information about the logic involved. A German company running an AI screening tool in recruitment has obligations under both instruments on documentation, transparency and human review, and the human review requirement is the one that fails most often in practice, because a review that consists of a manager clicking approve is not a review. The Deadline That Did Not Move The most useful thing about the Omnibus postponement is what it distracts from. The civil liability timetable was not postponed, and it bites sooner than the new high-risk dates. The revised Product Liability Directive, 2024/2853, must be transposed into German law by 9 December 2026. It introduces rebuttable presumptions of defectiveness for complex products, and software including AI systems falls inside its scope. Germany’s existing Produkthaftungsgesetz applies to AI software in principle, but the revised directive changes what a claimant has to prove, which is the variable that decides whether cases are brought. For a company, the exposure runs through two channels. The first is litigation: a claimant who does not have to prove the specific defect because the presumption applies is a claimant with a viable case. The second is insurance. Standard German commercial liability and professional indemnity policies typically do not extend affirmatively to AI errors without an explicit endorsement, and a firm that has checked its AI Act obligations and not its policy has checked the smaller of its two problems. That is the pattern behind all five myths. Each one directs attention to a date that moved and away from a date that did not, or to a penalty that is dramatic and away from a duty that is mundane. A company that reorganises its compliance function around December 2027 and leaves its product liability cover untouched has read the regulation correctly and the risk wrongly. Why These Five Travel The propagation mechanism is worth naming, because understanding it is the only defence against the next version of the same error. Law firm publications are not versioned. A guide written in early 2026 and updated in August may still contain sentences composed before the Omnibus, and readers have no way to see which sentences those are. One guide reviewed for this piece states plainly that it “still carried the pre-Omnibus position in several places”, that it had told German operators to plan for 2 August 2026, and that every instance has since been rewritten. That is an unusually honest note, and it is also a description of the entire genre. The headline number beats the tier structure because 35 million euros fits in a slide and three tiers do not. The word delay beats the phrase fixed commencement date because delay implies relief and commencement implies work. And a national law and a European regulation look identical to a reader who has never had to distinguish them, which means a German implementation story gets filed as a European weakening story. The fifth mechanism is arithmetic. Twenty-seven member states at twenty-seven stages of readiness produce twenty-seven different national situations. Any one of them, reported accurately, becomes false the moment it is generalised. A German firm reading that France has not finished its designations may reasonably conclude that nothing is operating anywhere, when the Bundesnetzagentur has had powers since July. There is a sixth mechanism that is harder to name and easier to observe: the incentive to be useful. A compliance publication that tells readers the deadline is fixed and most of their exposure sits in tiers two and three is less useful, commercially, than one that tells them a 35 million euro fine is coming. Alarm is a product. The firms that sell it are not lying about the statute, they are selecting the true sentence with the higher open rate. The defence is mechanical rather than intellectual. Before acting on any summary, check three things: the date the summary was updated, whether it cites a regulation number and an article, and whether it distinguishes the European instrument from the national implementing law. A document that fails all three is not necessarily wrong. It is simply not evidence, and in a calendar that has moved twice in eighteen months, evidence is the only thing worth planning against. Data basis Dates and tier amounts are taken from Regulation (EU) 2024/1689 as amended by Regulation (EU) 2026/1744, the Digital Omnibus on AI, which entered into force on 27 July 2026; the amendment replaced a standards-linked commencement mechanism with fixed dates of 2 December 2027 for Annex III and 2 August 2028 for Annex I. German institutional facts, including the KI-MIG adoption on 11 June 2026, its entry into force on 29 July 2026, the designation of the Bundesnetzagentur, the retention of BaFin and BfDI competences and the addition of 43 posts, are from reports of the Bundesnetzagentur announcement and from national implementation analyses. The figure of nine designated authorities among 27 member states as of June 2026 is from a compliance tracker published in October 2026. The Article 6 guidelines timeline is from the same tracker. Penalty tiers are quoted from Article 99, including the SME rule in Article 99(6). Limitations of the Five Tests Three limits apply. The consolidated text of Regulation 2026/1744 was not read directly; dates come from analyses that cite it, and one source could not confirm parts of the German implementation record against a primary legislative source. The nine-of-27 figure is a point-in-time count that will have changed. No German regulator or company was interviewed, so how these beliefs spread rests on published material, not testimony. Sources EUR-Lex — Regulation (EU) 2024/1689 laying down harmonised rules on artificial intelligence, Official Journal EUR-Lex — Regulation (EU) 2026/1744, the Digital Omnibus on AI, in force 27 July 2026 eyeon.ai — Germany’s KI-MIG enters into force, Bundesnetzagentur becomes central AI Act authority, July 2026 Confir — EU AI Act in Germany: enforcement, authorities and business obligations AI Law Radar — Germany: AI regulation and deadlines, checked October 2026 RegDossier — AI Act compliance deadlines: what applies now and what is delayed FutureCode — EU AI Act after the Digital Omnibus: what companies must have ready This article was prepared by the expert team at Global Infinity Labs, drawing on insights and data provided through its MCP data services. About Global Infinity Labs Global Infinity Labs is an AI innovation company specializing in MCP data services. Email: support@globalinfinitylabs.com
More
Korea Will Let SMR Developers Meet the Regulator Before They File SeaPRwire

Korea Will Let SMR Developers Meet the Regulator Before They File

SeaPRwire – South Korea’s nuclear regulator will open a preliminary review track for small modular reactors later this month, letting developers put a design in front of safety officials before they file for a licence. Around ten companies have signalled they intend to use it, and a few say they will submit as soon as it goes live, the head of the Nuclear Safety and Security Commission said. The distinction the new track creates is procedural. A licence application asks whether a specific reactor at a specific site can operate. A preliminary review asks a narrower question earlier: whether the design, as drawn, will survive the safety case that licensing will eventually demand. Choi Won-ho, who chairs the commission, described the purpose as reducing regulatory uncertainty for companies while letting his staff learn new designs before those designs are frozen into an application. Ten applications is a small number, and the list behind it is instructive. BEES is a domestic developer. TerraPower is American. Saltfoss Energy is Danish. A country building a review track for its own vendors has already found that its first customers are foreign. There is a sequencing problem in that queue. A foreign vendor’s design has already been shaped by its home regulator’s expectations, so the first batch of reviews will test how far Korean criteria can accommodate a reactor built to somebody else’s rulebook. That is a harder first case than a domestic design, and it arrives first. What the system does not do is shorten licensing. Nothing in the arrangement changes the safety standards a reactor must meet, and no design approved through the preliminary track holds a licence. The commission is rewriting those standards separately, in phases, with 2030 as the target for covering reactors of different designs and purposes (a scope far wider than the light-water fleet the current rules were written around). That rewrite is where the schedule risk sits. A review track running against standards that are themselves in motion can produce findings that later need revisiting, and the commission has not said how it will reconcile the two clocks: designs reviewed in 2026 and 2027 will be judged against rules that are scheduled to change by 2030. The scope of that rewrite is broader than the count of reactors suggests. Rules written around light-water units have to be extended to designs and purposes that the current framework does not cover, and each addition changes what a reviewer is checking against. Standards drafted after the first reviews begin will not be the standards those reviews were conducted under. For a developer, the arithmetic is simple even without the details. A licensing application that fails is the expensive outcome: years of documentation, a site, and capital committed against a design that the regulator has rejected. A review that fails earlier costs less, and a review that passes gives an investor something to point at before the first concrete is poured. That asymmetry explains the queue more than any incentive the government has offered. The international piece is not decorative. Korea’s regulator takes part in IAEA work on SMR regulation and is talking to the United States and Canada, both of which already run some form of pre-licensing review. Choi said consistency across borders matters. The practical reason is that a vendor designing one reactor for several markets wants one safety case, not four. If Seoul’s criteria diverge from Washington’s or Ottawa’s, the preliminary review becomes a local detour, not a step toward a global submission. Consistency is not recognition. Nothing in the commissioner’s account suggests Korea will treat another regulator’s safety finding as its own; the aim is comparable criteria, which still leaves a separate national review, a separate outcome and a separate bill. Export is the other half of the argument. Korea sent four reactors built on its own technology to the United Arab Emirates under a 2009 consortium deal, all in commercial operation by 2024, and signed for two units at Dukovany in the Czech Republic last year. Choi framed regulatory know-how as part of the export package, not an afterthought: transferring safety expertise to a host country, he said, matters as much as the reactor technology. Vietnam is the live case. It restarted its nuclear programme in 2024 and has asked the commission for help building a safety framework and training staff. That request is for the regulator, not the vendor. It is a different kind of export – slower to close, harder to invoice, and dependent on the same staff who are simultaneously reviewing SMR designs and rewriting standards. The agency’s other queue shows how thin that staff is. Ten reactors are in line for lifespan extensions at the request of Korea Hydro and Nuclear Power, and the commission has already granted ten more years to Kori units 2, 3 and 4, which have run for over four decades. Hanbit units 1 and 2 are expected in the first half of 2027, Hanul units 1 and 2 in the second half. Add the SMR track, the standards overhaul and monitoring of Japan’s release of treated water from Fukushima, which the commission says it samples at 78 points, and the workload is the binding constraint rather than the policy design. Several operational questions remain unanswered. Whether the preliminary review carries a fee, how long it takes, and whether its findings bind the later licence application are all unspecified in the roadmap. Those are the first three questions a developer’s regulatory affairs team asks, and they are usually answered before a programme is announced, not after. Those details decide whether the track is a genuine de-risking tool for developers or an early conversation with no contractual weight – and the developers deciding whether to apply this month will read them that way. Two things can be checked within a year. Whether the ten interested companies actually file, and whether the first design to pass preliminary review later clears licensing without substantial redesign. The second is the only measure that shows the track did what it was built for.
More
Readwise Opens an Ebook Store, With Its AI Features Waiting on Publisher Consent SeaPRwire

Readwise Opens an Ebook Store, With Its AI Features Waiting on Publisher Consent

SeaPRwire – Readwise launched Readwise Books on Monday in the United States: an ebook store that doubles as a reading tracker. Titles come from the big five publishers and others, which the company describes as millions of books. The app is free and currently in an invite-only beta. It is replacing two things that used to be separate. Kindle sells the book; Goodreads records whether you finished it. Readwise Books puts buying, reading and logging in one place and adds resolution to the logging: words read, pace, session length, how deep into a sitting a reader stayed. Taken as a store alone, this is the heaviest thing the company has attempted. Independent developers have spent years shipping reading trackers and almost none have gone near ebook retail, for a reason that is easy to find: Kindle holds roughly 83% of ebook sales once Kindle+ (formerly Kindle Unlimited) is counted, according to Goodereader’s tally. Readwise does not sell an e-reader and has no hardware position to defend. What it has is a decade of highlights and book notes, plus a subscriber base that pays monthly. The existing apps cost $7.99 a month each or $9.99 for both. The company has been bootstrapped from the start. Books bought from Amazon stay inside Amazon’s reader, and Readwise’s import path covers DRM-free files only. The store therefore does not begin with a library the customer already owns. It asks a reader to keep two bookshelves instead of one, and to trust that the new one still opens in five years. Running a store is also a different business from running a subscription. Wholesale terms, sales tax, refunds and the payment plumbing behind millions of titles are capabilities Readwise has not needed before, and the company has not said who supplies the catalog feed or how returns are handled. Discovery is the other unfinished piece. A store with millions of titles needs a way to surface them, and Readwise’s advantage there is the history it already holds: a recommendation drawn from what a reader highlighted carries more signal than a bestseller list. That signal runs only on books the app has seen, which is the same coverage limit the AI features face. Outside its own store, Readwise logs books bought elsewhere through a few side doors. It follows sessions through Kindle’s browser-based Cloud Reader, lets readers photograph a physical book to mark a page, accepts any DRM-free EPUB, and hands read-aloud to the system’s text-to-speech voice. The decision that shapes the product most is how the AI features are licensed. Session recaps, definitions and term lookups, phrase translation, and the ability to ask questions about the passage in front of you all switch on only with a publisher’s permission. Of the big five, only HarperCollins has agreed so far. That arrangement shows up in the reader’s hands. The same book bought from a consenting publisher gets recaps and questions; bought from another, the buttons are simply absent. Millions of titles sit in the store and only some of them can be processed by a model, and the line is drawn by contracts rather than by subject matter. Amazon does not have this problem. It is the store and the hardware maker, so it negotiates the terms with itself. Readwise went the other way on a second front. It publishes an API and runs an MCP server, so an AI agent can read a user’s library: research recommendations, build a books page on a personal site, or let a hackable e-reader log sessions automatically. That is a feature and also a transfer of leverage. Data that can leave cannot be held hostage, which means the same door that opens Readwise to other tools opens the exit for its users. The company calls its metrics a Strava for reading. In a blog post, co-founders Daniel Doyon and Tristan Homsi wrote that the wish to read, like the wish to exercise or eat well, arrives loaded with guilt, and that feeling bad about it changes nothing. Session tracking works on a different lever: it makes the reading you already do visible. That argument worked for running apps, and it runs into one difference here. Strava records roads you actually rode. A reading session records time and page turns, not what went in. The company says the most consistent user feedback is that people read more without goal-setting or streaks. Feedback like that cannot be checked from outside, and it cannot be separated from selection: someone willing to pay for reading statistics probably already reads. The metrics have a second use that has nothing to do with motivation. A tracker that knows what someone is reading has a reason to be opened every day, and a daily habit is what a $9.99 subscription is really selling. The store gives that habit somewhere to spend. Print books are fulfilled through Bookshop.org’s distributor and only some audiobooks are listed. Neither line carries ebook margins, and the company has not said whether it earns a commission on either. It has also not said how revenue splits between the store and the subscriptions. The store is US-only for now and requires an invite unless you already subscribe. Handing the door to paying customers first keeps support load down and puts the earliest buyers in the group most likely to tolerate a beta. Three things are worth watching. Whether the other large publishers follow HarperCollins, which decides whether the AI layer is the product or an exception. Whether the store converts existing highlight users into book buyers instead of letting them buy elsewhere and log here. And whether API usage turns into a cost line rather than a reputation. In the business history of reading, selling books earns thin margins and selling the experience of reading earns thinner ones. Readwise has bet on both at once: a free store to buy users, a set of features that must be negotiated publisher by publisher to buy subscriptions. Whether the arithmetic works rests on the publishers, not on how good the app is.
More
Omen Bought the Other Half of the Sensor It Sells to Data Centers SeaPRwire

Omen Bought the Other Half of the Sensor It Sells to Data Centers

SeaPRwire – Omen AI will pay $16 million in cash and stock for Aquatic Labs, a competitor that had been building its own real-time sensor for the water running through data center cooling loops. The company confirmed the deal on Monday. The two products measure different things. Omen’s sensor looks for elements dissolved in the fluid; Aquatic Labs’ looks at alkalinity. Putting both into one housing is supposed to give operators a reading they can act on instead of a number they have to interpret against a lab report that arrives three days later. The two measurements catch different failures. Corrosion and scale begin in the chemistry of the loop, and biological growth usually announces itself as a pressure drop that nobody reads until a heat exchanger is already fouled. A probe that reports both also cuts the number of sampling kits a facilities team keeps on site, which is the operational argument for consolidation. It is not an argument that either metric is better than the other. Cooling fluid is where a lot of money quietly disappears. When a valve starts to fail or bacteria take hold in a loop, the cheaper response is usually to dump the water and refill rather than risk fouling the equipment it protects. That means stopping work on racks worth more than the water ever was. Keeping the same fluid in service longer is the entire commercial case for monitoring it continuously, and it is a case Omen has been making since it raised a $31 million Series A in June (techcrunch.com/2026/06/29/omen-ais-plan-to-optimize-data-centers-is-all-wet/). The founders arrived from opposite directions. Zach Laberge left high school to start a company that ran fluid analysis for construction machinery dependent on hydraulics. Allan Adams spent most of his career as a physicist building ocean sensing instruments at MIT and the Woods Hole Oceanographic Institution before founding Aquatic Labs. Adams is now Omen’s chief science officer; Laberge runs the company. Their integration target is a single sensor, expected on the market early next year. Omen says its current units will be monitoring chips drawing 250 to 300 megawatts of power by the end of 2026, a slice of installed capacity Laberge puts at roughly $5 to $7 billion, with a goal of covering the equivalent of a gigawatt by the end of 2027. Put those numbers against the water itself. Data centers in the United States use 17 to 19 billion gallons a year for cooling, according to The Water Foundation, and that figure is expected to triple within five years. A monitoring product that reduces how often a facility drains and refills its loops touches both the water bill and the discharge permit, which is why Adams frames the municipal end of the pipe as part of the same problem: fluid leaves the building and enters a public system, and someone has to be able to show what is in it. The demand side has become noisier. Companies once floated as much as $4 trillion in AI infrastructure spending by 2030 (techcrunch.com/2026/02/28/billion-dollar-infrastructure-deals-ai-boom-data-centers-openai-oracle-nvidia-microsoft-google-meta/), and investors have spent recent weeks marking down the companies paying for it (techcrunch.com/2026/10/30/cracks-are-emerging-in-the-ai-spending-boom/). Omen’s answer is that its customers are not the ones deciding whether to build. “We’re working [with] customers on stuff they’re building today or have already built, and so it doesn’t really affect us because all of those projects were financed 12 months ago,” Laberge said. “Our view is, if there’s tightness, this is still going to be the biggest market in human history, even if you sliced it in half.” That argument holds for the next several quarters and gets weaker after that. A sensor installed in a plant that broke ground in 2025 is revenue no matter what happens to construction starts in 2027. A pipeline that depends on new plants does not have that protection, and the company has not said how much of its booked business runs past the current build cycle. The deal also thins out the supply side. Operators weighing continuous water monitoring have had at least two small vendors to compare against each other; after this acquisition, one of them belongs to the other. Nothing in the announcement says whether existing Aquatic Labs customers keep their contracts and their sensor firmware on the same terms. The engineering claim needs the same kind of scrutiny. Merging an ion sensor and an alkalinity sensor into one package is a materials problem as much as a software one: the two measurements want different conditions, and a combined probe has to hold calibration across the water chemistries used in different climates and different cooling designs. Omen has not published field data showing drift rates for the combined unit. The combined unit does not exist yet. Adams describes the result as a much richer picture of the water and the fluid. Richer is not the same as validated: the company has published no comparison of its readings against laboratory results, which is the standard the permits currently rest on. There is also a question of who the buyer becomes. Data center operators buy uptime. Water utilities buy compliance, on annual budget cycles, through procurement processes that treat new instrumentation as a capital item to be piloted for a year. Adams wants the same sensors measuring discharge into municipal systems, which is a reasonable extension of the technology and a much slower sales motion than the one Omen has been running with hyperscale tenants. What the deal actually buys, then, is a competitor’s chemistry expertise and a founder who can talk to scientists, paid for partly in stock. Sixteen million dollars is small against the cost of a single loop shutdown at a large campus, which is the comparison Omen would like operators to make. It is also small enough that the company will need another round before the combined sensor has a track record. Two things are checkable from here. Whether the integrated unit ships on the timeline the company gave, and whether operators will accept continuous readings in place of the lab samples their permits and maintenance contracts currently specify. The second is the harder one, and no sensor specification answers it.
More
COP17 Closed With a Roadmap, $2 Billion, and Four Years Left SeaPRwire

COP17 Closed With a Roadmap, $2 Billion, and Four Years Left

SeaPRwire – COP17 closed in Yerevan on Saturday with a document called the Yerevan Pathway, about $2 billion in new funding pledges, and four years left to deliver 23 biodiversity targets that a global review has already found the world is not on track to meet. The gap between those two facts is the story. A conference that ends with nearly 50 decisions and a named pathway has produced the machinery of a plan, not the outcomes the plan exists to produce, and the calendar is now shorter than the implementation cycle of most of what was agreed. What the pathway asks for is specific enough to check. Countries are to phase out subsidies that harm nature, align national budgets and economic decisions with the framework, and increase financial, scientific and technical support to developing countries. It also asks for stronger monitoring and reporting, which is the part with teeth, because a target nobody reports against cannot be judged missed. The nearly 50 decisions adopted cover protected areas and forests, wildlife management, invasive alien species, marine and coastal biodiversity, and synthetic biology. Most of them are guidance for national implementation, which means their effect is decided in capitals rather than in Yerevan. A decision that a ministry never reads has the same force as one that was never adopted, and the conference has no way to tell the two apart until reports come in. The funding announced is real money and modest relative to the problem. Nearly $2 billion was pledged, including $560 million from the Global Environment Facility’s latest replenishment, $500 million through the Species Recovery Alliance, and $330 million for the Value Nature Fund, which is meant to pull in private capital. The Asian Development Bank added a biodiversity bond and an investment incubator. None of the announcements came with a disbursement schedule, and pledges made at a conference are commitments of intent until a finance ministry writes them into a budget line. The channels matter as much as the totals. The Global Environment Facility is the established multilateral route, with an allocation process and recipient governments on the other end. The Species Recovery Alliance and the Value Nature Fund are newer vehicles, and the second is explicitly designed to raise money from private investors. When a conference reports a single total, it blends money that will be programmed by agencies with money that has to be raised from asset managers first. Neither the alliance nor the fund published a project pipeline in Yerevan, so both remain announcements until projects are named. Finance is the demand that recurs at every one of these meetings, and the pathway answers it the way previous outcomes did: by calling for more support to developing countries without attaching an amount or a schedule to the call. The countries asking have argued for years that they cannot align budgets with a framework whose targets assume money they do not have. Nothing adopted in Yerevan settles that. Two institutional changes will outlast the headline number. The Sevan Guidelines set the operating rules for a new permanent body that gives Indigenous Peoples and local communities a formal role in shaping global biodiversity policy, which converts a consultation habit into a standing seat. Separately, parties agreed new indicators for monitoring and accountability. Indicators sound administrative. They are how a voluntary framework becomes falsifiable: with agreed metrics, a country’s failure shows up in a table rather than in an argument. The 23 targets were adopted in 2022 under the Kunming-Montreal framework, and the review that preceded this conference concluded that the world is off track on them. That finding was not disputed in Yerevan. The dispute was over who pays and who reports, which is why the finance language and the subsidy language carry more weight than the number of decisions adopted. What that review can see is worth separating from what it cannot. National reports describe policies and programmes; they do not measure whether an ecosystem recovered. A country can record a subsidy reform and new protected areas without either changing the trend line the review tracks. Asking governments to align budgets with the framework is an attempt to move the measurement from intentions to money, which is why that clause carries more operational weight than the rest of the pathway. Nothing in the outcome creates an enforcement step. The pathway calls on governments; it does not oblige them, and the mechanism for a country that ignores it remains reputational. Astrid Schomaker, the convention’s executive secretary, put the test where it belongs: not what governments agreed in Yerevan, but what they change when they return home. That is an accurate description of how this process works and also an admission of where its leverage ends. The $2 billion should be read against that structure. Private capital vehicles like the Value Nature Fund and the ADB’s bond are attempts to move money that governments will not appropriate, and they come with the usual condition: investors need a return, which means projects that generate revenue, which is a narrower set than the ecosystems under pressure. What Yerevan did do is set up the next measurement point. COP18 meets in Ecuador with two years left on the targets, which makes the national reports filed between now and then the only place where the pathway can be tested. Ecuador also inherits the new body’s first budget and the first round of reporting against the agreed indicators, an agenda that assumes the machinery works before anyone has run it. If the subsidy commitments appear in budgets, the process has moved. If the reports arrive late or partial, the four years will pass the way the last four did. Hambardzum Matevosyan, who presided over the conference, described two weeks in which differences were bridged and commitments became decisions. Inger Andersen of UNEP said environmental multilateralism had prevailed again. Both statements are true of the room. Whether they are true of the decade depends on a set of documents that will be filed by finance and environment ministries, in national capitals, with no conference president in the chair.
More
MegaGeeks Inc. Unveils 2026 Strategic Expansion Plan to Drive 5G and Mobile App Ecosystem Synergy in Southeast Asia SeaPRwire

MegaGeeks Inc. Unveils 2026 Strategic Expansion Plan to Drive 5G and Mobile App Ecosystem Synergy in Southeast Asia

DENVER, CO - November 01, 2026 - (SeaPRwire) - MegaGeeks Inc. (MGK), a U.S.-headquartered digital innovation and 5G technology platform company based in Colorado, today announced the rollout of its 2026 global expansion initiative aimed at enhancing digital application distribution and 5G industry collaboration. Entering the Philippine market this year following invitations to support local digital infrastructure, MGK is advancing its mission to connect mobile application developers with authentic user engagement. By establishing a platform-based ecosystem, the company continues to bridge international technology capabilities with regional market opportunities across Southeast Asia. MegaGeeks operates a standardized digital management framework that translates application promotional needs into structured, experience-based user tasks. Through its platform services, MGK provides developers with multi-channel distribution support while enabling participants to engage in project collaboration and complete audited tasks under clear operational rules. Built on principles of transparency, technical innovation, and environmental and social governance (ESG), the company focuses on creating measurable digital reach and long-term value for global tech partners. "Our objective is to streamline how digital applications connect with real users across growing mobile markets," said Tim Taber, President and CEO of MegaGeeks Inc. "By combining compliant management systems with localized market execution, we provide a secure, efficient foundation for developers seeking sustainable user acquisition and digital transformation." Looking ahead, MegaGeeks will continue expanding its global partner network, deepening technology R&D, and promoting sustainable digital practices. The company remains committed to building an open, inclusive ecosystem that supports both local economic development and international technology cooperation. About MegaGeeks Inc. Established in Colorado, USA, in 2026, MegaGeeks Inc. (MGK) is a digital innovation company specializing in omni-channel mobile application promotion, 5G technology application support, and decentralized user engagement ecosystems. Guided by core values of compliance, efficiency, and mutual benefit, MGK delivers platform-based solutions and digital management services to partners worldwide. Media & Business Inquiries: MegaGeeks Operations Team Email: MegaGeeks999@gmail.com Website: https://www.mgkgeeks.com/
More
Renoa Has Its Own Fiber Name Now. The Blend Is What Has to Sell. SeaPRwire

Renoa Has Its Own Fiber Name Now. The Blend Is What Has to Sell.

SeaPRwire – Everbloom’s renoa became the first new fiber classification approved by the US Federal Trade Commission in 25 years, a decision that gives a material made from waste protein its own name on a label. It is a naming decision, not a performance standard. The fiber starts as scraps. Cashmere and wool offcuts, plus the down and feather lint that bedding manufacturers throw away, are ground into a powder, blended with a biodegradable biopolymer, and extruded to whatever length and diameter is needed to copy a target natural fiber. Everbloom has spent three years on the process and built its own materials-science model to search the formulation space; a cashmere substitute is the first product out of it. In the US, the FTC governs what a fiber may be called on a garment. Until a material has a generic name of its own, a brand describing it on a care label has to fold it into an existing category or fall back on a catch-all. A dedicated classification changes the paperwork rather than the yarn: it lets a 20 percent component appear in a blend as itself, which is the difference between a fiber that can be merchandised and one that has to be explained in a hangtag paragraph. Sim Gulati, the company’s co-founder and chief executive, walked me through samples at Everbloom’s office in New York, 15 floors above Fifth Avenue across from Bryant Park. A crewneck, a pair of gloves, a scarf. The scarf carried the most evidence. Gulati had worn and washed it for months and put it through a tumble dryer before I saw it. No pilling, no visible shrinkage, and the hand was still soft. That is a useful observation about one garment, made by the person selling it, on a sample knit to order. A scarf that survives a dryer is a data point. It is not a specification. The commercial plan is narrower than the fiber’s ambition. Everbloom is talking to a range of brands, and the first garments are expected to use renoa as a minority component, around 20 percent of a cashmere blend, with a launch targeted for the second quarter of 2027. The 80/20 swatch I handled was close enough to cashmere that I would not have picked it out of a rack by touch, and Gulati says the finishing steps that commercial garments go through should close whatever gap is left without costing the washability or the dimensional stability. Twenty percent is a sensible wedge for a new material, and it is also where the claims get easier. A minority component does not have to reproduce cashmere on its own; it has to disappear into a blend that still behaves like the thing customers already know. The price story works the same way. Cutting a fifth of the cashmere out of a sweater lowers the cost of the most expensive input without asking a shopper to accept a new hand-feel. What the samples do not settle is the part that decides whether this scales. Nobody has published a cost per kilogram at volume, an extrusion throughput figure, or a yield from a tonne of feather lint. The feedstock itself is a logistics question: bedding waste and mill offcuts exist in large quantities, but they are scattered across suppliers, and collecting, cleaning and grinding them into a consistent powder is a different business from buying bales of virgin fiber. Dyeability, blending behaviour with wool and synthetic staple, and the pilling performance of a 20 percent blend after 20 wash cycles are all outside what a single test scarf can show. Cashmere’s problem is not only price. Retail runs from a $7,900 cable-knit cardigan at Brunello Cucinelli to a $50 crewneck at Quince, and Loro Piana turned the material into a pillar of an LVMH division valued above EUR 11 billion. The supply side is uglier. The goats behind the fiber have been degrading rangeland across Central Asia, and a garment that cannot be machine washed adds a care burden that pushes buyers toward cheaper blends anyway. A substitute that survives a dryer addresses a real complaint, which is why the category approval landed with more force than a typical materials startup announcement. A generic name also changes what the material can be sold against. A brand that blends renoa into a sweater can list it as a component instead of describing the garment as cashmere plus something unnameable, which matters for the price claim as much as for the care label. It cuts the other way too. Once a fiber has a name, competitors can use it, and a category with one member stops being a differentiator. The 25-year gap says something about how rarely this happens. Fiber categories are not added on a schedule, and the agency’s process is not a fast one, so a new generic name is closer to a regulatory milestone than to a product launch. It also sets a floor for scrutiny: once a fiber can be named, it can be compared, tested against the same standard methods as the incumbents, and priced against them on a shelf. For brands, the near-term question is duller than the technology. Whether a label that reads 80 percent cashmere and 20 percent renoa sells better than one that reads 100 percent cashmere at a higher price depends on how the blend is presented, and on whether retailers treat the substitution as a story or as a cost saving. Everbloom’s own ambition is larger than the first garments, but the first garments are what will be judged. The tests worth watching are specific. A third-party pilling and shrinkage result on a commercial 80/20 knit, a published price per kilogram, and a named brand putting renoa on a label rather than in a press release. Until those exist, the strongest claim Everbloom can make is the one it has already earned: the material has a name, and a writer washed a scarf. When the first garments reach shelves next spring, I will be looking at the care label first.
More
Maldives Revenue Rose 5.6 Percent. Spending Rose 17 Percent. SeaPRwire

Maldives Revenue Rose 5.6 Percent. Spending Rose 17 Percent.

SeaPRwire – State revenue and grants reached MVR 33.36 billion in the year to 22 October, up 5.6 percent from MVR 31.60 billion over the same stretch of 2025, according to the finance ministry’s weekly fiscal report. Revenue and grants are reported as one figure, and the weekly table does not separate the two in the headline number. The 33.36 billion blends tax receipts, non-tax receipts and grants, which is why the tax line, up 9.8 percent, and the headline, up 5.6 percent, point in different directions. Expenditure in the same period rose 17 percent, to MVR 37.21 billion. The two numbers together describe the shape of the year better than either does alone. Revenue grew, and it grew on the strength of tax collection, which rose 9.8 percent to MVR 25.73 billion. Non-tax revenue fell 9.5 percent, and the ministry’s report notes that higher resort rent and Airport Development Fee receipts were not enough to offset declines elsewhere in that category. Tourism carried the tax side. Tourism goods and services tax brought in MVR 8.87 billion, up 5.7 percent, and green tax added MVR 1.78 billion, up 2.6 percent. Two levies tied to the same industry produced MVR 10.65 billion, a little over two-fifths of all tax receipts. Concentration of that kind cuts both ways. It means a single bad season, a single change in source-market demand or a single shift in room rates moves a large share of the government’s income at once. It also means the ministry’s revenue forecasting is, in practice, a tourism forecast with a tax rate applied. Import duties show why the small lines cannot carry a weak year. At 11 percent growth they added roughly MVR 280 million, about three times what a single percentage point of tourism GST is worth. The arithmetic behind that concentration is worth stating plainly. A 10 percent shortfall in the two tourism levies would remove about MVR 1.07 billion, roughly four times the primary surplus recorded so far. The budget has no second line of that size to absorb it. The rest of the tax base grew faster from a smaller base. Business and property tax rose 21.8 percent to MVR 5.97 billion, import duties 11 percent to MVR 2.82 billion, and general GST reached MVR 4.46 billion. None of those lines is close to the size of the tourism levies, which limits how much they can compensate in a weak year. On the spending side, the growth is concentrated in commitments that are hard to reverse. Salaries and pensions accounted for MVR 12.05 billion. Subsidies rose 58.6 percent to MVR 4.31 billion, an increase the report links to higher fuel costs. Aasandha, the state health insurance scheme, cost MVR 1.94 billion, and grants to local councils rose 15.9 percent to MVR 2.08 billion. Recurrent spending came to MVR 32 billion of the MVR 37.21 billion total, leaving capital expenditure at MVR 5.21 billion. Within that, land reclamation and land management spending rose 89.7 percent, and outlays on buildings and land reached MVR 1.69 billion. Add up the four recurrent lines the report itemises, salaries and pensions, subsidies, Aasandha and council grants, and they come to MVR 20.38 billion, about two thirds of all recurrent spending. Those are the parts of the budget that do not flex with revenue. The balance lines are the ones worth reading twice. The state recorded a primary surplus of MVR 0.27 billion, which is the balance before interest payments. The overall fiscal balance was a deficit of MVR 3.85 billion. The gap between the two, roughly MVR 4.12 billion, is interest. A weekly cash report is useful for a different reason than an annual budget. It shows the order in which money arrives and leaves, which is why a primary surplus in October does not settle what the full-year deficit will be once the fourth quarter is booked. What the report does not provide is the other half of the interest story. There is no debt stock, no average interest rate and no maturity profile in the weekly table, so the MVR 4.12 billion cannot be broken down into principal it replaces and rate it pays. A primary surplus alongside an overall deficit is a statement about the interest line rather than about the government’s day-to-day finances. It says the operating position is marginally positive and the debt service is not. Three limits apply to all of this. The 22 October cutoff leaves more than two months of the year, including the peak inbound season, outside the figures. The weekly report is a cash-basis snapshot rather than a full-year projection against the approved budget. And a single period comparison against 2025 says nothing about whether the ratios are inside the fiscal rules the government has set for itself. The two sides of the ledger are growing at rates that do not converge on their own. Tax receipts rose 9.8 percent. Subsidies rose 58.6 percent. Salaries and pensions, the largest single line, are set by formula and not by the revenue outcome. Closing that gap is a decision about rates or about commitments, and the weekly report contains neither. What the report does establish is the structure that the rest of the year will run on. A recurrent-heavy budget, financed mainly by two taxes collected from one industry, with a debt service bill larger than the primary surplus. If tourism receipts hold through December, the primary balance stays positive and the deficit is a financing question. If they do not, the same recurrent commitments do not move, and the adjustment has to come from somewhere else. That is the number to watch in the next weekly release, and the one after it. Not the headline revenue figure, which is doing what the tax base allows, but the subsidy line and the interest line, which are doing what the commitments require.
More
England’s 10 Percent Is Fixed. The Boundary Map Is Where the Argument Will Be. SeaPRwire

England’s 10 Percent Is Fixed. The Boundary Map Is Where the Argument Will Be.

SeaPRwire – From 2 November 2026, a covered development consent application in England has to arrive with an outline biodiversity gain plan and draft requirements, because the national policy objective of at least 10 percent gain now attaches to the date the paperwork is filed. An application filed on 1 November does not. It stays under the old test for the length of its examination. That gap of a single day is not a transitional footnote. It is the mechanism the rule runs on. Parliament and Defra put the trigger on the application date rather than on the consent decision, so two schemes with the same footprint, the same habitat and the same local authority can face different evidence burdens depending on when their lawyers queued the file. For a promoter, the date has become a commercial variable. Filing before the cutover buys an examination under the old test, but it also means defending a scheme against a policy that has already moved. Waiting buys a cleaner policy position and hands over a gain plan, a boundary map and a 30-year management obligation that have to be priced before the application goes in. The obligation itself sits at the end of the process, in the Secretary of State’s hands. Consent cannot be granted for a new covered order unless the Secretary of State is satisfied that the statutory objective is met. The Examining Authority reads the gain plan during examination and reports; the satisfaction test is applied at the decision, which means an applicant who treats the plan as an annex to be tidied up late is arguing about it in the wrong order. Scope is narrower than the phrase British infrastructure suggests. The objective reaches specified applications under sections 37 and 104 or 105 of the Planning Act 2008, plus projects directed into the regime under section 35. It covers nationally significant infrastructure in England, including intertidal components out to the mean low-water mark. Marine environment beyond that line is out, and so is anything consented through a hybrid bill. Data centres get their own instrument. A published biodiversity gain statement applies to data-centre NSIPs, which is not the same population as every server building that goes through ordinary planning permission. A developer who has spent two years on a warehouse-scale scheme under the Town and Country Planning Act does not inherit the NSIP statement by describing the building as a data centre. The number is the easy part. Ten percent is a floor, applicants use the statutory biodiversity metric, and the rule permits going above it. The baseline is the hard part, and for data-centre schemes it is defined by disclosure. The baseline takes in habitats inside the order limits that the development will damage plus the areas used to deliver gains. Habitat that is never touched can be left outside the baseline entirely. The boundary map has to separate four things: affected ground, gain areas, retained habitat counted inside the boundary, and unaffected habitat excluded from it. A developer who draws the boundary tightly reports a small baseline and a modest gain obligation. A developer who draws it broadly, or whose authority insists on a wider one, reports a larger number for the same site. Both can satisfy a 10 percent objective while delivering very different amounts of habitat. That is why the examination will spend its time on the map and the metric inputs rather than on the percentage, which nobody is negotiating. Delivery has its own constraints. Gains can be delivered on site, through registered off-site habitat, or a mixture of the two. Government credits are described as a last resort, not a routine purchase. Significant on-site gains have to be legally secured and then managed and monitored for at least 30 years, and the data-centre statement goes further, saying habitat should generally be maintained for the remaining life of a longer-running project. Thirty years of management is a contractual obligation with a cost attached, and it lands on whoever owns the land after the asset is sold. That is a different kind of commitment from a planting schedule attached to a construction programme, and it is the part of the rule most likely to change financing terms more than design choices. Defra kept the figure at 10 percent after respondents argued for more, and gave alignment with the Town and Country Planning Act regime as the reason. The consistency argument is defensible: a data-centre promoter moving between the two regimes should not face a different percentage depending on which door the project goes through. It also means the NSIP route inherits a number that was set for a different consenting system, with a different evidence culture and a much larger volume of small applications. Off-site delivery raises a supply question the rule does not answer. A registered habitat bank has to exist, be measured by the same metric and be able to promise management for three decades. Whether that market clears at the volumes the NSIP pipeline implies is the constraint nobody has tested, because until this month no applicant had to buy before filing. What nobody has tested yet is how authorities will read the inputs. Whether an Examining Authority accepts a narrow order-limits baseline, how it treats habitat that is degraded but inside the boundary, and what condition wording it will accept as legally securing 30 years of management are all open. The first application filed after the cutover will set the working interpretation, and it will do so faster than any guidance note. For a promoter with a scheme at the pre-application stage, the practical sequence is now fixed. The gain plan is a submission document, not a post-consent deliverable, and the map that defines the baseline has to exist before the application is filed. Anyone who filed in the last week of October has bought themselves an examination under the old test. Anyone filing from 2 November has bought a boundary argument. The percentage was never going to decide these projects. The map, the baseline and the 30-year management obligation will.
More
Vietnam’s E-Commerce Grew 44% in 2026. Its Parcel Count Grew 13.7%, and the Gap Is the Story SeaPRwire

Vietnam’s E-Commerce Grew 44% in 2026. Its Parcel Count Grew 13.7%, and the Gap Is the Story

Four claims that circulate in every Vietnam investor deck, checked against YouNet ECI, Metric.vn and the withholding decrees now in force SeaPRwire – In the first half of 2026, four platforms sold VND 291.6 trillion of goods in Vietnam. That is the number in the 2026 slide pack, usually rendered as 44.11% growth, usually followed by the sentence that the market has never been stronger. The same deck will tell you that in the first half of 2026 Shopee led with 54.5% and TikTok Shop closed at 43.4%, that official Mall stores are the only safe place to sell, and that the tax authorities have finally closed the loophole that let cross-border sellers undercut everyone. Each of those sentences is defensible on its own. Taken together they describe a market that is growing at more than twice the rate of the parcels moving through it, in which the two leaders hold 97.9% of the money and an unknown share of the sellers, and in which a compliance regime that began in February 2025 has had eighteen months to change behaviour. Whether it has is a question nobody in the deck answers, because the deck is selling the growth line and the growth line is doing the work. This piece takes the four claims one at a time. Where a number is solid, I say so. Where two official-looking numbers disagree, I put them side by side rather than picking the flattering one. Where the arithmetic does not reproduce a figure that everyone repeats, I show the division. The Claim, as It Appears in the Deck The version I keep hearing in Hanoi and Ho Chi Minh City goes like this. Vietnamese e-commerce is the fastest-growing large market in Southeast Asia; it grew 44% in the first half of 2026 to VND 291.6 trillion, or about US$11.1 billion at the prevailing rate; Shopee and TikTok Shop together hold 97.9% of it; Mall stores, 2.79% of the store count, now take 34.2% of revenue; and the 2025 tax decrees have pushed the grey-market cross-border sellers out, which is why the growth is finally “healthy”. The people saying this are not lying, and most of them have a source. The problem is that the sources measure different things, on different windows, with different denominators, and the composite sentence they produce is not something any single dataset supports. Start with the one figure that travels furthest: 44.11%. It appears in a presentation by the E-commerce Development Centre, a unit under the Ministry of Industry and Trade, reported in October 2026 with the accompanying shares of 54.5% and 43.4%. It is a revenue figure for four platforms, and it is real in the sense that someone computed it from platform data. What it is not is a like-for-like growth rate, and the reason is visible in a second number published five weeks earlier. Two Numbers for One Half-Year, 26.8 Trillion Dong Apart On 12 August 2026, the Vietnam office of China’s Ministry of Commerce relayed a report from Nguoi Lao Dong on the same six months. The figure there was VND 264.8 trillion, growth of 19%, down from 23% in the first half of 2025. Shopee 54.5%. TikTok Shop 43.4%. Same period. Same shares, to one decimal place. Two totals for the same six months of 2026 that differ by VND 26.8 trillion, and two growth rates that differ by 25 percentage points. Table 1: One half-year, two published totals Source H1 2026 GMV (VND trillion) Stated growth Implied H1 2025 base (VND trillion) YouNet ECI, via Nguoi Lao Dong, 12 Aug 2026 264.8 +19% 222.5 E-commerce Development Centre, Oct 2026 291.6 +44.11% 202.4 Difference 26.8 25.1 points 20.1 The implied bases are the interesting part. Divide the August 2026 figure of 264.8 by 1.19 and you get 222.5. Divide the October 2026 figure of 291.6 by 1.4411 and you get 202.4. Neither base is obviously wrong, but they cannot both be the true 2025 half-year. One dataset has restated the base downward by VND 20.1 trillion, which is roughly what happens when a measurement house tightens its panel, drops a category it used to count, or switches from GMV booked at order creation to GMV net of cancellations and returns. That is not a scandal. It is what panel data does. But it means the sentence “the market grew 44%” and the sentence “growth slowed from 23% to 19%” are both being published in the same year about the same six months, and the second one is the one that matters for anyone deciding whether to hire a warehouse team in Binh Duong. My reading, and it is a reading rather than a finding: the 44.11% is a revenue-based growth rate off a restated base, and the 19% is a like-for-like growth rate off the original base. The shares agree because shares are computed inside each dataset and are robust to restatement. The growth rates do not agree because growth is exactly the thing a restatement moves. There is a test that would settle it, and it is cheap. Ask both houses for their 2024 and 2025 half-year totals on the current panel definition. If the 2025 base comes back near 202.4, the 44% is arithmetic and the 19% is a different panel. If it comes back near 222.5, the 44% is a base effect dressed as growth. Nobody in the deck has asked. Myth One: TikTok Shop Has Already Passed Shopee The most confidently repeated claim in the market is that TikTok Shop has overtaken Shopee in Vietnam. It has not, in any dataset I can find, and the claim survives because a rolling twelve-month window can be made to say almost anything. In October 2026, Metric published a twelve-month rolling series to April 2026 showing TikTok Shop at roughly US$5.96 billion and a 44% share, up from 33%, with Shopee down from 61% to 53%. That is a real finding: a ten-point swing in twelve months. Read quickly, it says the leader is about to be passed. Read carefully, it says the challenger gained ten points and is still nine behind. The half-year data says the same thing more soberly. In the first half of 2026 it was Shopee 54.5%, TikTok Shop 43.4%, a gap of 11.1 points. In the first half of 2025 the gap was wider. The direction is not in dispute. The crossing is. And the mechanism behind the narrowing has already weakened. TikTok Shop’s revenue grew 27% in the first half of 2026, against 148% in the same period of 2025. When a challenger’s growth falls by four-fifths while the leader grows 15%, the gap stops closing at the rate the rolling chart implies. Extrapolating a twelve-month swing into a crossing date is the single most common error in this market’s commentary, and it is an error of arithmetic, not of judgement. Why the claim spreads is worth one paragraph, because it is not stupidity. Platform-share stories are how agencies sell services. “The incumbent is finished” is a better pitch than “the incumbent has 54.5% and is growing 15%”, and the rolling window supplies a chart that looks like a crossing. The chart is honest. The sentence attached to it is not. Myth Two: Forty-Four Percent Growth Means Consumers Are Buying More Here the arithmetic is simple enough to do on a phone, and it changes the story completely. In the first half of 2026 revenue grew 44.11% while units sold grew 13.67%. Divide one by the other and the average order value rose 26.8%. In dong terms, the average basket went from about VND 371,000 to VND 470,000 if you take the E-commerce Development Centre’s own totals and the reported unit growth, and NielsenIQ’s separate measurement puts the basket at US$14.20, up US$1.80 year on year, which is 14.5% in dollar terms and consistent in direction. So the market did not sell 44% more things. It sold 13.7% more things at 26.8% higher prices. Those are different facts with different consequences. Table 2: What the growth is made of Component H1 2026 change What it implies Platform revenue +44.11% The headline Units sold +13.67% Volume demand Implied average order value +26.8% Mix and price, not volume Active stores with revenue about 436,000 A thinning seller base Stores excluding Mall -27% year on year Exit, not entry A 26.8% rise in basket size in six months is not a normal consumption pattern. It is what happens when the cheapest categories shrink, when subsidy-driven low-ticket orders stop being worth fulfilling, and when the platforms stop paying for growth. YouNet ECI’s own analyst put it plainly in August 2026: the market is entering a stable phase that tracks overall retail rather than outgrowing it on platform incentives. That is a mature-market sentence. It is being printed underneath a 44% headline. Both are in the same report. For a seller, the difference is decisive. Volume growth of 13.7% supports a fulfilment and packaging business. Price-led growth of 26.8% supports brands, authorised distributors, and anyone who can defend a price. Vietnam’s own data says the second group is winning: Mall stores are 2.79% of stores and 34.2% of revenue, their count fell 6% while their revenue rose 54%, and the average Mall store’s revenue rose about 63.8%. Myth Three: The Small Seller Is the Backbone Every market entry memo about Vietnam contains a version of this line: the market is fragmented, small sellers dominate, and a platform that serves them will inherit the growth. The store-count data points the other way. About 436,000 stores generated revenue on the major platforms in the first half of 2026. The number of ordinary, non-Mall stores fell 27% year on year in the first half of 2026. Mall stores fell 6% in count but rose 54% in revenue. Average revenue per store rose 44% on Shopee and 65% on TikTok Shop in the first six months of 2026. Put those together and you get a market where the seller base is contracting while revenue per surviving seller is rising. That is consolidation, and it is happening faster on the platform usually described as the small seller’s friend. TikTok Shop’s store-level average grew 65% because the stores that remained were better, not because the ones that left were replaced. The consequence is structural rather than moral. A platform whose growth comes from 436,000 surviving stores has less need for the long tail than one whose growth comes from store count. That shows up in take rates, in traffic allocation, and in how much a new seller has to spend on live-commerce production before the algorithm notices them. The long tail is not the customer any more. It is the inventory. The 25x That Nobody Can Reproduce Here is a small case of a number that has escaped its source. The claim, repeated in Chinese and Vietnamese trade coverage through 2026, is that a Mall store’s average revenue is 25 times that of an ordinary store. The two inputs are solid: Mall stores are 2.79% of stores and 34.2% of revenue. Do the division. A Mall store’s revenue index is 34.2 divided by 2.79, which is 12.3 times the all-store average. An ordinary store’s index is 67.7 divided by 97.21, which is 0.696 times the average. The ratio between them is 17.6, not the 25 that 2026 trade coverage reports. Table 3: The Mall premium, recomputed Measure Mall stores Ordinary stores Ratio Share of store count 2.79% 97.21% 0.029 Share of revenue 34.2% 67.7% 0.505 Revenue index vs all stores 12.3 0.70 17.6 Seventeen-point-six times is still an enormous premium. It is not 25, and the gap between 17.6 and 25 is the difference between a fact and a slogan. If a plan assumes a Mall listing triples a seller’s revenue relative to an ordinary listing, this arithmetic says it does something closer to eighteen times, which should make anyone suspicious of the plan rather than reassured by it. Numbers that flatter too much are usually measuring something else. Myth Four: The Tax Net Closes the Door The fourth claim is the one I have the most sympathy for, because the policy changes are real and they are recent. On 18 February 2025, Decision 01/2025/QD-TTg ended the VAT exemption for imported parcels valued at VND 1 million or less. Since February 2025 customs has run an automated collection mechanism against a flow of 4 to 5 million low-value orders a day. From 1 July 2025, Decree 117/2025/ND-CP required platforms with payment functions to withhold and remit tax on behalf of household and individual sellers. From 1 January 2026, the unified flat-rate regime was replaced: platforms with payment functions withhold VAT and personal income tax at source, platforms without a payment function leave the seller to declare, and sellers under VND 200 million in revenue can claim a refund of what was withheld. Decree 68/2026/ND-CP set the household-business threshold at VND 500 million of revenue, not profit. That is a genuine tightening. It is not a door closing, and the arithmetic of who it hurts is more specific than the commentary suggests. Table 4: The cost stack for a seller turning over VND 5 billion a year Line Basis Annual cost (VND million) Share of revenue Platform commission at 7.5% Low end of published Q2 2026 rate cards 375.0 7.5% Platform commission at 9.5% High end of the same cards 475.0 9.5% VAT withheld on goods 1% of revenue 50.0 1.0% Personal income tax withheld 0.5% of revenue 25.0 0.5% Total platform and tax cost Commission plus 1.5% 450.0 to 550.0 9.0% to 11.0% Reported total operating cost 30% of GMV, Momentum Works 1,500.0 30.0% Read the last two rows together. In the 2026 schedule the tax that everyone is arguing about is 1.5% of revenue. The platform take in the Q2 2026 rate cards is 7.5% to 9.5%. Total seller operating cost, including fulfilment, returns, livestream production and ads, is around 30% of GMV in the 2026 Momentum Works estimate. The withholding decree moved the smallest line in the stack, and it moved it in a way that a seller can plan for, because it is a percentage rather than a negotiation. What the decrees actually changed is the floor. A seller who cannot absorb 1.5% was never covering 30%. A seller who can now has a cost line that is predictable, which is worth something to anyone trying to borrow against future cash flow. The grey-market operators who were arbitraging the VAT exemption on VND 200,000 items lost an edge worth about VND 20,000 a parcel. That is a real loss and a small one. The commentary that says the net “closes the door” also tends to get the rate wrong. One widely circulated advisory puts the platform withholding at 5% VAT plus personal income tax. The 5% rate is the services schedule. Goods distribution in Vietnam is 1% VAT plus 0.5% personal income tax, a combined 1.5%, which is what the decree applies to marketplace sales of physical goods. In 2026 a seller who budgets 5% will over-reserve by more than three times, and a seller who reads only the Chinese-language summaries will conclude the market has become uninvestable when it has become 1.5% more expensive. What the Withholding Actually Changed Three things, and none of them is exit. First, it made revenue visible. Once the platform withholds at source, the seller’s declared revenue and the platform’s transaction record are the same number. That ends a specific kind of under-declaration, and it also ends the practice of using a partner’s name to open a store while declaring only withdrawals. Second, it moved compliance cost onto the platform. Shopee’s cost of services was US$9.5 billion in FY2025 and its sales and marketing expense US$3.55 billion. A withholding obligation is an engineering and reconciliation cost of a few million dollars, not a strategic threat to a company of that size. For a five-person seller, the same obligation is a monthly accounting task. Third, it made the small-seller exemption a cliff rather than a slope. The VND 500 million threshold under Decree 68/2026 is revenue, not profit, and a seller doing VND 40 million a month crosses it in month thirteen. There is no phase-in. That cliff, not the 1.5%, is the part of the policy that will change behaviour, because it punishes growth at a specific revenue point. What Survives the Debunking Four claims, four different outcomes. The 44% is real as a published number and unreliable as a growth rate; the same six months also grew 19% depending on the panel. TikTok Shop has closed ten points and has not crossed; the crossing story depends on a rolling window and a growth rate that has already collapsed from 148% to 27%. The small seller is not the backbone; the seller base shrank 27% while revenue per survivor rose, and Mall stores at 2.79% of count take 34.2% of revenue. The tax net did tighten, by 1.5% of revenue on goods, not by the 5% that some advisories report, and its real effect is a cliff at VND 500 million rather than a wall at the border. What is left is a market that is consolidating, ageing into price-led growth, and becoming legible to the tax authority for the first time. That is a less exciting story than the one in the deck and a much more useful one, because each of those three adjectives implies a different investment. If you want one indicator to settle the whole argument, watch the gap between revenue growth and unit growth. In a healthy volume market the two converge. In the first half of 2026 they were 30.4 percentage points apart. If that gap narrows to single digits while revenue growth holds above 15%, the market is genuinely selling more to more people, and the 44% was a base effect. If revenue growth falls to 15% and the gap stays wide, Vietnam has imported the Korean pattern: a mature, brand-led, price-driven market where the platforms are utilities and the growth story is over. Both are fine outcomes. They require opposite plans. Data Basis: Six Numbers, Six Documents Every figure above traces to a document, and the method is reproducible. The H1 2026 platform total of VND 291.6 trillion and the 44.11% growth rate come from the E-commerce Development Centre presentation reported on 10 October 2026 in Hue, alongside the 54.5% and 43.4% shares. The VND 264.8 trillion total and 19% growth rate come from YouNet ECI’s H1 2026 report as relayed by Nguoi Lao Dong on 12 August 2026 and republished by the Vietnam office of China’s Ministry of Commerce. Unit growth of 13.67%, the 2.79% Mall store share, the 34.2% Mall revenue share, the 436,000 revenue-generating stores and the 27% decline in ordinary stores come from Metric’s October 2026 release. The VND 1 million VAT threshold, the 4 to 5 million daily low-value parcels, Decree 117/2025 and Decree 68/2026 come from Vietnamese customs and tax guidance as summarised by two trade advisories in 2026. The 30% seller operating cost, the 89% to 85% platform share of total e-commerce and the US$9.5 billion Shopee cost of services come from Momentum Works’ Southeast Asia report and Sea’s FY2025 disclosure. Basket size of US$14.20 and the 41.5% cash-on-delivery share come from NielsenIQ and State Bank of Vietnam data cited in the same trade reports. The two growth rates were not reconciled because the underlying panels were not published. I have said which one I think is like-for-like and why, and marked it as a reading rather than a finding. Anyone with access to both houses’ 2024 and 2025 half-year totals can settle it in an afternoon, and until someone does, the honest version of the headline is a range: somewhere between 19% and 44%, with the shares agreeing and the growth disagreeing. Sources YouNet ECI via Nguoi Lao Dong, republished by MOFCOM Vietnam — Vietnam e-commerce growth slows in H1 2026, 12 August 2026 E-commerce Development Centre, Ministry of Industry and Trade, via Vietnam.vn — Hue e-commerce conference reporting H1 2026 totals, 9 October 2026 Metric.vn data via 10100.com — Vietnam platform shares and Mall store economics, October 2026 Momentum Works, Southeast Asia E-Commerce 2026 — regional GMV, platform shares and seller cost structure, April 2026 Vietnam Government, Decision 01/2025/QD-TTg as summarised by 10100.com — end of the low-value import VAT exemption, February 2025 Vietnam tax and e-commerce decree summary, ASEAN trade briefing — Decree 117/2025 and Decree 68/2026 withholding rules, July 2026 Bain, e-Conomy SEA 2026 — regional digital economy totals including Vietnam, October 2026 This article was prepared by the expert team at Global Infinity Labs, drawing on insights and data provided through its MCP data services. About Global Infinity Labs Global Infinity Labs is an AI innovation company specializing in MCP data services. Email: support@globalinfinitylabs.com
More
A 30-Person Firm in Taiwan Needed AI: Three Quotes, One Contract, NT$1.4 Million Apart SeaPRwire

A 30-Person Firm in Taiwan Needed AI: Three Quotes, One Contract, NT$1.4 Million Apart

Why the cheapest Copilot rollout, the middle RAG pilot and the on-premise box are not versions of the same purchase, priced line by line for 2026 SeaPRwire – The company makes fasteners. Thirty people, a factory in Gangshan and an office that answers quotation requests from German and American buyers in two languages, four thousand active part numbers, and a stack of supplier PDFs that nobody has ever read systematically. The owner wants a system that turns an incoming inquiry into a draft quotation with the right part number, the right tolerance and the right price band, and he wants it before the busy season. That is the whole brief. It is also, in Taiwan in 2026, the point where three completely different purchases get presented as the same thing. I spent two weeks building the three cost stacks for this firm, using published licence prices, the government’s own consulting rate card, and the arithmetic that determines whether a seventy-billion-parameter model fits on one machine. The gap between the cheapest and the dearest path, over the three years from 2026 to 2029, is NT$1.41 million. The gap between what each path delivers is larger than that. The Trouble, in One Purchase Order Here is the actual work, because the cost model is meaningless without it. A buyer in Stuttgart sends a PDF drawing and a sentence: can you supply this in A4 stainless, 12,000 pieces, delivered in eight weeks. Someone in Gangshan opens the drawing, reads the tolerance callout, searches a spreadsheet for a matching part number, checks a second spreadsheet for the last price quoted to a similar buyer, checks a third file for the current material surcharge, and types a quotation into a template. If the part is new, they add a line for tooling. If the buyer is new, they add a payment-terms paragraph that only two people in the company know how to word. Twenty minutes when the part is familiar. Two hours when it is not, and the two hours is where the margin goes, because a slow quote loses to a fast one and a wrong tolerance loses the account six months later. Everything below is an attempt to cut those two hours. That is the only outcome that matters, and any vendor who cannot tell you how their product touches those two hours is selling something else. Why the Obvious Fix Does Not Work The obvious fix is to buy seats. Microsoft 365 Copilot sits inside Outlook and Word, which is where the work already happens, and the licence is a line item rather than a project. It fails on one detail that nobody mentions in the demo: the drawings are scans. A PDF exported from a CAD system carries text. A PDF that a buyer printed, stamped and photographed does not. Copilot reads what is in Microsoft Graph, and what is in Microsoft Graph is a folder of scanned PDFs plus four thousand rows spread across three Excel files that disagree with each other about part-number formatting. The second failure is permissions. Copilot answers with whatever the signed-in user can already open. If the quotation template sits in a folder that the whole company can read, Copilot will quote from the version that was superseded in March. Cleaning that up is not an AI project. It is three weeks of someone deciding who owns which folder, and it has to happen before the licences go live, not after. The third failure is arithmetic. Let me do it, because it is the number that ends the argument. Table 1: Path one, eight seats of Copilot for a thirty-person firm Line Basis Year one (NT$) Years two and three (NT$) Licences at list 8 seats x NT$675 x 12 64,800 64,800 Administration 4 hours a month at NT$350 16,800 16,800 Internal learning 96 hours at NT$350 33,600 0 Total 115,200 81,600 Three-year total 278,400 The published price has three versions in 2026 and they are not close. In the July 2026 Taiwan price list, Copilot Business lists at NT$675 per user per month, is promoted at NT$578.58 on annual billing, and costs NT$810 on monthly billing. The enterprise SKU is NT$965. Eight seats on monthly billing is NT$77,760 a year in 2026 before anyone learns anything, which is more than the annual saving from one avoided wrong quotation. That is the honest case for path one: it is cheap, it is reversible, and it will make eight people slightly faster at writing emails. It will not read a scanned drawing. 7.4% and 86% Describe the Same Country Before choosing, it is worth knowing what everyone else chose, and Taiwan’s numbers are unusually good at showing why this decision is confusing. The Ministry of Economic Affairs’ 2025 white paper on small and medium enterprises, published in 2026, found that 7.4% of Taiwanese SMEs had adopted or were planning to adopt AI. The OECD average cited alongside it in the same 2026 comparison is 39%. A separate survey by the Artificial Intelligence Foundation put the overall AI index for Taiwanese industry at 46.32 in 2026, up from 36.77 in 2025, with information and communications at 52.7 but traditional manufacturing at 43.87 and retail at 44.86. A 2026 Institute for Information Industry MIC survey found 28% of manufacturers had adopted AI. Then, in October 2026, Meta published a survey conducted by YouGov between 6 August and 2 September 2026 across nine Asia-Pacific markets: 86% of Taiwanese SMEs said they had started using AI, and 94% planned to apply it to marketing and content within twelve months. Seven point four percent and eighty-six percent. Both are about Taiwanese small and medium enterprises in 2026. Both are probably measured correctly. The difference is the verb. “Using AI” means at least one person on at least one device has opened a chatbot. “Adopted” means a process changed. A factory owner who asks ChatGPT to polish a German email is using AI. A factory whose quotation process runs through a retrieval system is adopted. Taiwan has a lot of the first and very little of the second, and the 12-fold gap between the two numbers is the most useful statistic in the country for anyone selling into this market, because it tells you where the purchase actually is. It is not in the licence. It is in the process. Path One: Buy Seats What you get for NT$278,400 over three years is eight people who draft faster. What you do not get is a system that knows your part numbers. The failure is not subtle and it is not the model’s fault. Copilot’s answer quality is bounded by the quality of the corpus it is allowed to read. A firm with 4,000 part numbers in three spreadsheets and a folder of scans has a corpus problem, and a seat licence does not solve corpus problems. It solves writing problems. There is a version of path one that works, and it is worth naming because it is what most Taiwanese SMEs actually do: buy three seats, give them to the people who write the most English, and accept that the quotation logic stays manual. That costs NT$104,000 over the three years to 2029 including learning time, and it delivers a real but small return. The mistake is buying thirty seats and expecting the quotation problem to disappear. Path Two: Buy a Working System The middle path is to have someone build the retrieval layer: parse the drawings, normalise the part numbers into one index, encode the pricing rules, and put a chat interface on top that cites which document each answer came from. The cost driver here is not the model. It is the person-days, and Taiwan publishes a number for those. The Republic of China Information Service Industry Association’s 2026 cost-estimation standard for outsourced information services lists a project manager including management consulting at NT$223,083 per person-month for the first category, and NT$289,641 for the third. Divide the 2026 rate by 22 working days and a person-day is about NT$10,140 before expenses and tax. A three-month pilot at four person-days a month is twelve days, NT$121,680 in 2026 money, plus a project fee. Market quotes for small integration work in Taiwan start around NT$50,000 and go up with scope. Add sixty internal hours at NT$350 for the people who have to explain the pricing rules, and year one lands at NT$192,700. Table 2: Path two, a three-month retrieval pilot with an integrator Line Basis Year one (NT$) Years two and three (NT$) Integrator days 12 days at NT$10,140 121,680 81,120 Project fee Market floor for small integration 50,000 30,000 Internal hours 60 hours at NT$350 21,000 0 Total 192,700 111,100 Three-year total 414,900 This is the only path that produces the thing the owner asked for: a draft quotation with a cited source. It is also the only path with a dependency, because the integrator owns the pipeline and the firm owns the data, and the handover document is the difference between an asset and a subscription. What it does not buy is a model that speaks good German. A retrieval system built on a mid-size open model will quote the right part number and write a clumsy sentence. For a quotation, that is the correct trade. Nobody loses an order because the email reads awkwardly. They lose it because the tolerance is wrong. Path Three: Buy a Machine The third quote will be the largest and it will arrive with the words “data sovereignty” in the covering email. It is a two-GPU server running an open-weight model inside the factory, and the arithmetic of whether it fits is public. A model’s weight memory is parameters times bits per parameter divided by eight. In the 2026 open-weight catalogue, seventy billion parameters at sixteen bits is 140 gigabytes, which does not fit on any single accelerator a small firm can buy. At four bits it is 35 gigabytes, which fits on one 48-gigabyte card with room for a small context, and at eight bits it is 70 gigabytes, which needs two. Add the KV cache, the operating system, the vector index and the headroom that keeps latency tolerable under three concurrent users, and the honest configuration for a 70B model is two 48-gigabyte cards in a chassis that can cool them. In Taipei channel pricing in October 2026 that chassis, with the CPU, memory and NVMe to feed it, sat around NT$1.25 million. That is an estimate from component prices, not a quotation, and it excludes the room, the UPS and the person who will be on call. Table 3: Path three, a 70B-class model on premises Line Basis Year one (NT$) Years two and three (NT$) Server with two 48GB accelerators Channel estimate, October 2026 1,250,000 0 Integration 25 days at NT$10,140 253,500 0 Internal hours 120 hours at NT$350 42,000 0 Operations Power, part-time admin 48,000 48,000 Total 1,593,500 48,000 Three-year total 1,689,500 Three years of path three costs NT$1,689,500. Three years of path one, from 2026 to 2029, costs NT$278,400. The difference is NT$1,411,100, which is the number in the headline and roughly one year of gross profit for a firm this size. There is a fourth thing in the quote that is not a line item: the model choice is constrained before the price is. A Taipei deployment consultancy’s 2026 guide notes that open-weight models from Chinese vendors are typically excluded at procurement review in Taiwan’s public sector and regulated industries, even when run entirely offline, because the constraint is supply-chain security rather than data egress. For a private fastener exporter that constraint does not bind. For anyone selling to a Taiwanese state-owned enterprise or a bank, it removes the cheapest capable models from the list and pushes the hardware requirement up a tier. The procurement rule, not the benchmark, decides the invoice. The Number That Decides It: Scanned Pages Between paths two and three there is a factual question that settles most of the argument, and it is not about model quality. It is about how many of the 4,000 part drawings in the 2026 archive are scans. A text-layer PDF can be parsed in milliseconds by open-source tools. A scan needs optical character recognition, and OCR on a stamped engineering drawing with a tolerance callout in a rotated annotation is where accuracy falls apart. If 80% of the 2026 corpus is scans, the retrieval system will cite the wrong revision and the project fails for a reason that has nothing to do with the model. If 80% is CAD-exported text, the same system works. So the first deliverable of any pilot is not a chatbot. It is a count. Take 200 drawings at random in the first week of the project, run them through a text extractor, and record how many return usable text. That exercise costs one person two days, NT$20,280 at the 2026 rate card, and it tells you more about feasibility than any benchmark table. Which Path, Under Which Condition The decision rule I would actually use, written as instructions rather than principles. If fewer than 30% of the drawings carry a text layer, stop. Neither path two nor path three will work, and the money belongs in digitising the archive first. That is a scanning and indexing project, not an AI project, and it costs less. If the firm already lives in Microsoft 365, has clean permissions, and the quotation logic is simple enough to fit in a paragraph, buy eight seats and stop there. NT$278,400 over three years is a fair price for a 10% speed gain on writing. If the drawings are mostly text, the part numbers can be normalised into one index, and someone in the firm can own the rules, buy the pilot. NT$414,900 over three years is the cheapest path that changes the process. If a customer contract requires that data never leaves the building, the on-premise box is not optional and the NT$1.69 million is a compliance cost rather than an AI cost. Budget it as such, and put it next to the ISO audit fee, not next to the software line. Two of those four conditions are about documents and one is about contracts. None of them is about which model scores higher on a leaderboard, which is the thing every vendor wants to talk about. What I Would Sign For this firm, in this order: pay for the 200-drawing count first, then the pilot, then decide whether the box is needed. The reason is not that the middle path is cheaper than the box, although it is. The reason is that the pilot, run in 2026, produces the artefact that makes every later decision cheaper: a normalised index of 4,000 part numbers with the source document attached to each row. That index is worth having even if the chatbot is abandoned, because it is the thing that lets a new salesperson answer a tolerance question without walking to the factory floor. The box does not produce it. The seats do not produce it. The integrator produces it, and it stays. Taiwan’s own numbers say most firms will buy the seats, because 86% are already “using AI” and a licence is a decision one person can make on a credit card. The 7.4% who changed a process did something harder, and the gap between those two groups is where the next five years of competitive difference in Kaohsiung’s fastener cluster will be decided. It will not be decided by which model they picked. It will be decided by whether anyone counted the scans. Data Basis and the Four Costs the Quote Leaves Out The three stacks use published prices wherever a published price exists and state the assumption wherever one does not. Copilot Business at NT$675 list, NT$578.58 annual promotional and NT$810 monthly, and the enterprise SKU at NT$965, are from Microsoft Taiwan’s pricing page as checked on 29 July 2026, excluding 5% business tax. The NT$223,083 first-category person-month rate is from the Information Service Industry Association’s 2026 cost-estimation standard for outsourced services, inclusive of salary, management fee and public fee, exclusive of other direct costs and tax. Dividing the 2026 rate by 22 working days gives NT$10,140. NT$350 per internal hour is an assumption: a NT$56,000 monthly salary plus 19% employer burden, divided by 176 hours, rounded down. Replace it with your own number and every table moves proportionally. The 70B memory arithmetic uses parameters times bits divided by eight. The NT$1.25 million chassis is an October 2026 component-price estimate, not a vendor quotation, and it is the softest number in this piece. The 7.4% SME adoption rate is from the Ministry of Economic Affairs 2025 white paper published in 2026; the 86% figure is from a Meta-commissioned YouGov survey of 3,983 SME owners across nine Asia-Pacific markets, fielded 6 August to 2 September 2026; the 46.32 industry AI index is from the Artificial Intelligence Foundation’s 2026 survey. Four costs are missing from all three quotes and they are the ones that decide the outcome. The permission cleanup before any seat goes live, which is three weeks of someone senior. The OCR pass over the archive, which is priced per thousand pages and quoted by nobody. The person who owns the pricing rules and will be interrupted forty times in the first month. And the cost of the wrong quotation that ships before the system is trusted, which is the only line in the model that has a customer’s name on it. Sources Microsoft Taiwan, Copilot pricing — Copilot Business and enterprise seat pricing, checked 29 July 2026 Microfusion, Microsoft 365 Copilot cost and licensing guide — NT$675, NT$578.58 and NT$965 price points, 4 August 2026 Yutuo Tech, what AI adoption costs across three delivery models — four-column cost model and TISSA 2026 rate card, 2026 TAIDE project, model releases — Gemma-3-TAIDE-12b-Chat-2602 and the 131K-context 8B release, 2026 LargitData, on-premise AI deployment guide — weight memory arithmetic, inference stack comparison, procurement constraints on model origin, 2026 Taiwan Today, Ministry of Economic Affairs AI adoption programme — 2,058 companies assisted, 91% SMEs, NT$900 million in subsidies, 2026 Chung-Hua Institution for Economic Research, on the AI divide — AIF 2026 index of 46.32, MIC 28% manufacturing adoption, MOEA 7.4% SME figure, 22 October 2026 Artificial Intelligence Foundation and Dun and Bradstreet SME survey — 63.1% of SMEs still in early stages, 86.7% without an executed investment decision, 2026 Meta-commissioned YouGov survey of SMEs in nine Asia-Pacific markets — 86% using AI, 94% planning marketing use, 91% wanting guidance, 27 October 2026 This article was prepared by the expert team at Global Infinity Labs, drawing on insights and data provided through its MCP data services. About Global Infinity Labs Global Infinity Labs is an AI innovation company specializing in MCP data services. Email: support@globalinfinitylabs.com
More
Four Ways to Keep a Gulf Fleet Online, Priced to the Riyal and the Saudi Border SeaPRwire

Four Ways to Keep a Gulf Fleet Online, Priced to the Riyal and the Saudi Border

Three buying tasks run through local SIMs, a GCC roaming add-on, a travel eSIM and fixed wireless, with every 2026 tariff line counted AsiaPresswire – Start with one ratio. A Saudi prepaid plan in the 2026 tariff sells 100 gigabytes for SAR 115, which is SAR 1.15 per gigabyte, or about 31 US cents. A Saudi business roaming add-on in the same year sells 100 gigabytes for BHD 33, which is about 88 cents per gigabyte. The second product is nearly three times the price of the first for the same unit, sold by a telecoms group to companies that would never accept a threefold markup on anything else. That ratio is not a mistake. The two products are not the same thing sold at different prices, and the difference is precisely what a fleet manager, a consultancy and a pop-up retailer are each buying. But the ratio is also not the number that should decide the purchase, because neither buyer consumes 100 gigabytes. Once you price the bucket the buyer is forced to buy against the bytes the buyer actually uses, the ranking inverts, and it inverts differently for each of the three tasks below. This is an accounting exercise, not a coverage test. No network probes were run. Every figure traces to a published tariff sheet, a regulator filing or an operator annual report, and the arithmetic is written out so it can be checked. Three Tasks, Four Products, One Exchange Rate The three tasks are real procurement shapes, not illustrations. A fleet of 40 vehicles moving between Saudi Arabia, the United Arab Emirates and Qatar, 12 months, 3 gigabytes per vehicle per month for telematics and driver apps. A 12-person consultancy with one office in Dubai and quarterly trips to Riyadh, 6 gigabytes per person per month, most of it in the office. A retail kiosk in Riyadh that needs 200 gigabytes and a local number for 30 days, and nothing after that. The four products are the four things an enterprise buyer in the Gulf is actually offered. Table 1: Four connectivity products, what they cost per gigabyte at list Product Published example Price Data Cost per GB Term Local prepaid stc sawa Flex SAR 115 100 GB $0.31 4 weeks Local business postpaid stc Mofawtar from SAR 90 plan-dependent not comparable 12 months GCC roaming add-on stc Bahrain GCC 30 days BHD 33 100 GB $0.88 30 days GCC roaming add-on stc Bahrain KSA 30 days BHD 22 80 GB $0.73 30 days Roaming pass, short stc Bahrain GCC 3 days BHD 11 10 GB $2.93 3 days Unlimited roaming pass Zain KSA GCC weekly SAR 339 14 GB at full speed $6.46 7 days Daily passport Vodafone Qatar daily QAR 35 1 GB $9.62 1 day Travel eSIM, large HelloRoam KSA 20 GB $37.49 20 GB $1.87 30 days Travel eSIM, small HelloRoam KSA 5 GB $13.49 5 GB $2.70 30 days Fixed wireless stc Business Link 5G SAR 344 to 1,149 unlimited flat 24 months Exchange rates are the pegs: 3.75 riyals, 3.64 riyals, 0.376 dinars to the dollar. Tariffs include VAT where the operator states it, which in 2026 is 15% in Saudi Arabia and 10% in Bahrain. The Rate That Matters Is Per Gigabyte Used Divide the bucket by the need and the ranking changes. In 2026 the average telematics unit in a Gulf fleet uses about 3 gigabytes a month. The cheapest local plan a Saudi operator would sell a business in the 2026 price list is a 100-gigabyte prepaid bundle at SAR 115. You cannot buy 3 gigabytes. You buy 100 and use 3, which puts the effective cost at SAR 38.3 per gigabyte used in 2026, or $10.22. The headline rate was $0.31. The GCC roaming add-on is worse in absolute terms and better in relative ones. BHD 33 buys 100 gigabytes in the 2026 Bahrain tariff, so 3 gigabytes used costs $29.26 per used gigabyte. The rate card said $0.88. The gap between the headline and the effective rate is a factor of 33 in 2026, and it is the largest distortion in the table. The travel eSIM is the only product that sells a bucket close to the need. The 5-gigabyte plan at $13.49, quoted in September 2026, covers the month with 2 gigabytes spare, and 3 gigabytes used works out to $4.50 per used gigabyte. The headline rate, $2.70, is only 1.7 times the effective rate. Table 2: Headline rate against effective rate at 3 GB per month Product Bucket bought Headline $/GB Used GB Effective $/GB used Distortion Local prepaid, Saudi 100 GB 0.31 3 10.22 33x GCC roaming add-on 100 GB 0.88 3 29.26 33x Travel eSIM, 5 GB 5 GB 2.70 3 4.50 1.7x Travel eSIM, 20 GB 20 GB 1.87 3 12.50 6.7x There is a reason the buckets are sized this way, and it is not indifference to small buyers. A prepaid bundle is priced against the cost of the SIM, the registration record, the dealer commission and the churn risk, not against the marginal cost of a gigabyte. A 3-gigabyte bundle would carry the same fixed costs over one-thirtieth of the revenue, so operators do not sell one. The enterprise add-on is priced against the value of a single contract covering three countries, which is why its per-gigabyte rate is higher than a domestic prepaid plan and lower than a short-dated pass. Both prices are rational. Neither is quoted in the unit the buyer needs. This is the whole comparison in one table. The product with the lowest rate card is the second most expensive in practice. The product with the sixth-lowest rate card is the cheapest. Nothing about the networks changed, and no operator misled anyone; the buyers simply bought the wrong denominator. Task One: Forty Trucks Across Three Borders Now apply it to the fleet, with the costs that do not appear on any tariff sheet. Option one, local SIMs. Each vehicle needs a Saudi line, a UAE line and a Qatari line, because a Saudi prepaid SIM roaming into the UAE at standard rates is charged per megabyte. Forty vehicles times three countries is 120 lines in 2026, and each one needs its own registration. The Saudi line costs SAR 115 a month; UAE and Qatari prepaid lines are assumed at $20 each per month, which is an assumption, because neither operator publishes a comparable business prepaid rate in a form that can be quoted. Annual data spend in 2026: $33,920. Option two, a GCC roaming add-on on a single Saudi line per vehicle. Forty lines at BHD 33 a month is BHD 15,840 a year in 2026, or $42,128. This buys 100 gigabytes per vehicle per month, which is 33 times the requirement, and it buys one contract instead of three. Option three, a travel eSIM per vehicle. Forty 5-gigabyte plans a month at the September 2026 rate of $13.49 is $6,475 a year. This is the cheapest data line in the comparison by a factor of five, and it comes with the fewest guarantees: no local number, no service level, no corporate invoice in most cases, and terms of service written for travellers rather than for 40 vehicles that never move. Table 3: Twelve months for a 40-vehicle fleet at 3 GB per vehicle per month Line Local SIMs GCC add-on Travel eSIM Data and line fees $33,920 $42,128 $6,475 Lines to administer 120 40 40 Registration burden 3 regimes 1 regime none Management hours 540 156 176 Management cost at $35/hour $18,900 $5,460 $6,160 Total, 12 months $52,820 $47,588 $12,635 Cost per vehicle per month $110 $99 $26 Same task. Same three countries. A 4.2-fold spread between the cheapest and the dearest route in 2026, and the ranking is the reverse of the rate card. The Invoice Is Not the Cost The management hours in Table 3 are the part that procurement usually leaves out, and they are what makes the middle option competitive with the cheapest one. One hundred and twenty lines across three countries is not a data purchase. It is a registration project. A Saudi prepaid line requires identity registration tied to a resident or visitor record. A UAE line requires an Emirates ID or passport registration at a counter. A Qatari line requires its own. Each of the 120 lines has to be renewed on a different cycle, and when a truck is impounded or a driver leaves, someone has to chase the line. At an assumed loaded cost of $35 an hour for a fleet administrator in Dubai, 1.5 hours of registration per line plus a quarter-hour a month of renewal is 540 hours, or $18,900. That is more than half the data bill, and it is a permanent cost, not a one-off. The eSIM option has the opposite profile. Forty profiles, two hours each to install and test, then a top-up that takes twelve minutes a month across the whole fleet. That is 176 hours in the first year, $6,160. The add-on option sits between the two in 2026: one contract, one registration regime, 156 hours. Two conclusions follow, and they are the ones a procurement committee should hear. First, at 3 gigabytes per vehicle, no Gulf operator will sell you the right size, so the effective rate is set by the smallest bucket available rather than by the headline price. Second, when the management cost is included, the option that looks 5 times cheaper on data is only 3.8 times cheaper in total, and the option that looks 22% more expensive on data is actually 10% cheaper than local SIMs. Task Two: Twelve Consultants Who Barely Travel The second task is where the comparison stops mattering, and that is a finding rather than a gap. Twelve people, one Dubai office, four Riyadh trips a year with six people travelling. Data in the office in 2026: 12 people times 6 gigabytes is 72 gigabytes a month, but office data comes from fixed broadband or fibre, not from mobile. The mobile requirement is the travel slice: 6 people times 4 trips times 5 gigabytes is 120 gigabytes a year, bought in five-gigabyte eSIM chunks at $13.49, which is $324 a year. Local SIMs in both countries for all twelve staff would be $5,760 a year in 2026, and would deliver a service nobody needs, because the office already has fibre. So the entire decision is worth $324. Against that, the cost of choosing is not zero: a procurement review, a vendor comparison, a policy document and a monthly reconciliation cost more in hours than the service costs in money. The correct answer for Task Two is to stop analysing and buy the cheapest thing that works, and the correct answer for a consultant selling into this account is to walk away. This is the boundary condition that most connectivity comparisons miss. The comparison only has meaning above a threshold, and for a professional services firm with fewer than about 50 mobile-heavy staff in the Gulf, that threshold sits above the entire bill. The threshold is worth stating as a number because it is the only finding in this piece that saves more money than any tariff negotiation. Below roughly $10,000 of annual mobile data spend, the administrative cost of a competitive tender exceeds the spread between the best and worst supplier. Above $50,000, the spread in Table 3 is large enough that the tender pays for itself in the first quarter. Between those two numbers, the decision should be made on contract terms rather than on price, because the terms are what generate the invoices nobody budgeted for. Task Three: A Kiosk That Needs Thirty Days and Gets Twenty-Four Months The third task is the one where the contract term, not the tariff, decides the outcome. A retail kiosk in Riyadh needs 200 gigabytes and a local number for 30 days in the fourth quarter of 2026. The obvious enterprise product is stc’s Business Link 5G fixed wireless, which is designed for premises without fibre, includes a router, and comes in three speeds: 100 megabits at SAR 344 a month, 200 at SAR 459, and 500 at SAR 1,149, all including 15% VAT. The 500-megabit tier is SAR 27,576 over the 24-month minimum term, or $7,354, for one month of use. The 100-megabit tier is SAR 8,256, or $2,202, over the same 24-month term. There is no monthly option: the only contract duration stc offers on that product is 24 months. Table 4: One kiosk, 30 days, four ways to buy 200 GB Option What you commit to Cost for the 30 days Cost of the commitment Business Link 5G, 500 Mbps 24 months at SAR 1,149 $307 $7,354 total Business Link 5G, 100 Mbps 24 months at SAR 344 $92 $2,202 total Prepaid, two 100 GB bundles none $61 $61 Travel eSIM, ten 20 GB plans none $375 $375 The cheapest compliant answer is two prepaid bundles: SAR 230 for 200 gigabytes, a local number included, no term. The most expensive is the enterprise product that a procurement team would instinctively choose, because it is the one with a contract, an invoice and a support line. The prepaid route has a cost the table does not show. Registration requires an identity record, and a kiosk operated by a foreign retailer may not have one. That is why the enterprise product exists, and in 2026 it is a legitimate reason to pay $7,354 for a month of connectivity. It is not a reason to describe the purchase as a data plan. What the Tariffs Cannot Tell You Four things sit outside every number above, and each of them can reverse a decision. Permanent roaming rules. Consumer eSIM terms are written for travel. A fleet that leaves 40 profiles in place for 12 months through 2026 and 2027 is exactly the pattern operators classify as permanent roaming, and the remedy is usually suspension rather than a surcharge. Ask for the clause before the pilot, not after. Local numbering. Telematics units that receive commands by SMS need a real mobile number, and a data-only eSIM cannot receive one. If the fleet’s platform sends SMS triggers, only the local SIM and the roaming add-on options qualify, and the $12,635 option disappears. Invoice and VAT recovery. A travel eSIM bought on a personal card is not recoverable input tax. At 15% Saudi VAT, converting $6,475 of eSIM spend into $42,128 of invoiced corporate spend costs $35,653 in cash and recovers $5,486 in tax. The net premium for a compliant invoice is about $30,000 a year, which may still be the right purchase. Coverage at the actual sites. stc reported 12,120 5G sites in Saudi Arabia at the end of the first half of 2026, and e& reported 251.5 million connections across its footprint with 16.5 million in the UAE. National totals say nothing about a warehouse in Dammam or a border post at Batha. The only number that settles it is a drive test on the route. Data Basis: Nine Tariff Lines and One Exchange Rate Every figure in the tables can be recomputed from the following. stc Bahrain’s business roaming add-ons for 2026: KSA one day BHD 5.5 for 9 GB, seven days BHD 11 for 20 GB, 15 days BHD 16.5 for 50 GB, 30 days BHD 22 for 80 GB; GCC three days BHD 11 for 10 GB, seven days BHD 16.5 for 25 GB, 15 days BHD 22 for 50 GB, 30 days BHD 33 for 100 GB; all VAT inclusive at 10%. Zain Saudi Arabia’s GCC Unlimited offer, 2026 postpaid tiers: SAR 79 for 12 hours, SAR 99 for one day, SAR 219 for three days, SAR 339 for seven days, with a fair-use cap of 2 GB per day and 1 Mbps thereafter; out-of-offer data SAR 1.575 per megabyte. Vodafone Qatar’s 2026 postpaid tariff: daily passport QAR 35 for 1 GB, weekly QAR 100 for 3 GB, GCC roam-like-home weekly QAR 125, standard roam-like-home weekly QAR 150 and monthly QAR 500. stc’s Business Link 5G 2026 tariff: SAR 344, 459 and 1,149 a month for 100, 200 and 500 megabits, 24-month contract, CPE included, available only where the site has no fibre. stc sawa Flex at SAR 115 for 100 GB and Mofawtar business postpaid from SAR 90 a month are the 2026 consumer and business entry points. Travel eSIM prices for Saudi Arabia are HelloRoam’s published September 2026 rates on the stc 5G network: $3.99 for 1 GB over 7 days, $8.99 for 3 GB, $13.49 for 5 GB, $22.99 for 10 GB, $37.49 for 20 GB, all 30 days except the first. UAE plans in the same September 2026 comparison start at $1.95 per gigabyte. Operator scale figures: e& reported AED 38.1 billion of revenue and 251.5 million connections for the first half of 2026, with 16.5 million users in the UAE; du reported 9.3 million users; stc reported SAR 40.11 billion of revenue, 30.3 million mobile users and 12,120 5G sites for the same half. The $35 hourly loaded cost for a fleet administrator and the $20 monthly cost of a UAE or Qatari prepaid line are assumptions, and they are the only two inputs not taken from a published source. Both are marked where they appear. Change either and the tables move, but the ranking between the eSIM and the local-SIM option holds until the administrator’s hourly cost falls below about $9, at which point local SIMs become competitive on total cost and still lose on registration lead time. Sources stc Bahrain, business roaming add-ons — KSA, GCC, UAE and global roaming tariff lines, 2026 Zain Saudi Arabia, GCC Unlimited offer — weekly and daily GCC passes with fair-use terms, 2026 Vodafone Qatar, postpaid tariff notification — passport packs and GCC roam-like-home pricing, 13 September 2026 stc, Business Link 5G — fixed wireless tiers, 24-month term and pricing, 2026 stc, business and consumer plan portal — sawa Flex and Mofawtar entry pricing, 2026 eSIMRated, Saudi Arabia plan comparison — HelloRoam tier pricing verified 20 September 2026 eSIM vs Roaming, Saudi Arabia rates — carrier roaming charges against eSIM rates, 2026 e&, investor relations — first half 2026 revenue and connection counts stc, investor relations — first half 2026 revenue, mobile users and 5G site count This article was prepared by the expert team at Global Infinity Labs, drawing on insights and data provided through its MCP data services. About Global Infinity Labs Global Infinity Labs is an AI innovation company specializing in MCP data services. Email: support@globalinfinitylabs.com
More
NASA Wants Hubble at 600 Kilometers. The Request Comes Without Money. SeaPRwire

NASA Wants Hubble at 600 Kilometers. The Request Comes Without Money.

SeaPRwire – NASA published a request for information on 29 October asking companies how they would raise the Hubble Space Telescope, service it in place, or bring it down safely. Replies are due 30 November. Any mission would have to fly by 2032. The calendar runs on two clocks. Companies have 30 days to answer a document that asks them to outline a mission, and any resulting flight would have to happen within roughly six years of that answer. Hubble has no propulsion of its own. It orbits at roughly 470 kilometers, high enough that the residual atmosphere is thin but not absent, so the orbit decays year by year. The telescope is 36 years old, and it has been dropping since the last shuttle crew left it in 2009. The three options are not variations on one plan. A boost changes the orbit and nothing else. Servicing means reaching the telescope and working on it. Disposal means a controlled re-entry rather than an uncontrolled one, which requires the same docking capability as the other two. In every case the company supplies the rocket, the servicing spacecraft and the mission operations, and a crew if the mission needs one. The three missions also ask different things of the visiting vehicle. A boost needs thrust and navigation. Servicing needs a mechanical interface and the ability to work while holding position. Disposal needs enough control authority to choose where the telescope comes down. A company able to do one of these cannot necessarily do the other two. None of that is funded. NASA has not committed to buying a mission and has set no money aside for one, which makes this a market survey rather than a procurement. The document sets a floor for a boost at 600 kilometers and requires that the telescope not be damaged on the way. That is higher than the 583 kilometers Columbia left it at in 2002, and well above the 470 it has fallen to since. NASA’s own analysis puts re-entry in 2033 or 2034. The agency estimates a 10 percent chance by September 2032 and a 50 percent chance by December 2033. The telescope is heavy, and an uncontrolled fall leaves a small but non-zero chance that debris reaches people on the ground. That is the reason disposal sits on the list beside the two options that keep the observatory working. This is the second time the agency has asked industry for ideas and the third time it has looked for outside help. In 2022, Jared Isaacman, then a private astronaut, offered to pay for most of a crewed Hubble mission on SpaceX’s Dragon. NASA collected eight responses that year and decided in 2024 not to pursue a reboost. “If there are innovative and cost-effective ways to extend the life of an asset already on orbit, we owe it to the American taxpayer and the scientific community to explore them,” said Isaacman, who is now the agency’s administrator. A crewed visit is harder to arrange than it was four years ago. SpaceX plans to retire Crew Dragon by 2030, and NASA has already turned to Boeing for additional astronaut flights. Isaacman expects this round to draw robotics companies, according to Ars Technica. Several startups are already raising money for hardware that would refuel or reposition spacecraft in orbit. Swift, the agency’s smaller gamma-ray observatory, shows what the alternative looks like. Its science mission ended on 20 October, after drag below 275 kilometers made steady observations impossible. NASA expects it to re-enter within weeks. The agency had hired a startup, Katalyst Space, to catch Swift and lift it. The robot ran into trouble and never reached the telescope. The US Space Force now expects it down within days, the Associated Press reported. Most of it will burn up, though some dense tungsten parts and mirror segments may survive. The attempt ended before contact, which is the step all three options depend on. Hubble has one thing Swift does not: a soft-capture mechanism, fitted by astronauts on the last shuttle servicing mission in 2009, built so a visiting vehicle can dock without a hard jolt. Anyone bidding for a boost inherits that fixture. It makes the docking problem smaller. It does not make it small. A boost is the cheapest of the three in principle and the least useful if an instrument fails next year. Servicing buys time on the instruments but needs a vehicle able to hold station alongside the telescope while the work is done, and the request leaves the scope of that work to whoever answers it. Disposal produces no science and still requires a docking, which is why it is the option least likely to draw a bid. A request for information is not a solicitation. It commits the agency to nothing. The science case for keeping the telescope up does not rest on sentiment. Hubble observes in visible and ultraviolet light, and astronomers do not expect a replacement for that combination before the Habitable Worlds Observatory in the 2040s. A re-entry in 2033 would open a gap measured in a decade or more. NASA’s own schedule puts the Habitable Worlds Observatory in the 2040s, which is the earliest point at which that gap could close. The commercial side has changed since 2022. In-orbit servicing has moved from concept studies to funded hardware, and the companies most likely to bid are the ones building refuelling and inspection vehicles for commercial satellites. A Hubble mission is a different order of job, and respondents have until 30 November to say how they would do it. The request names no price range and no budget line, which leaves respondents to estimate what the agency would treat as reasonable, and to decide how much engineering detail to expose before any contract exists. Whether any of this produces a mission depends on three things the request does not settle: a price the agency can defend, a budget line that does not exist yet, and whether 600 kilometers buys enough years to justify the flight.
More